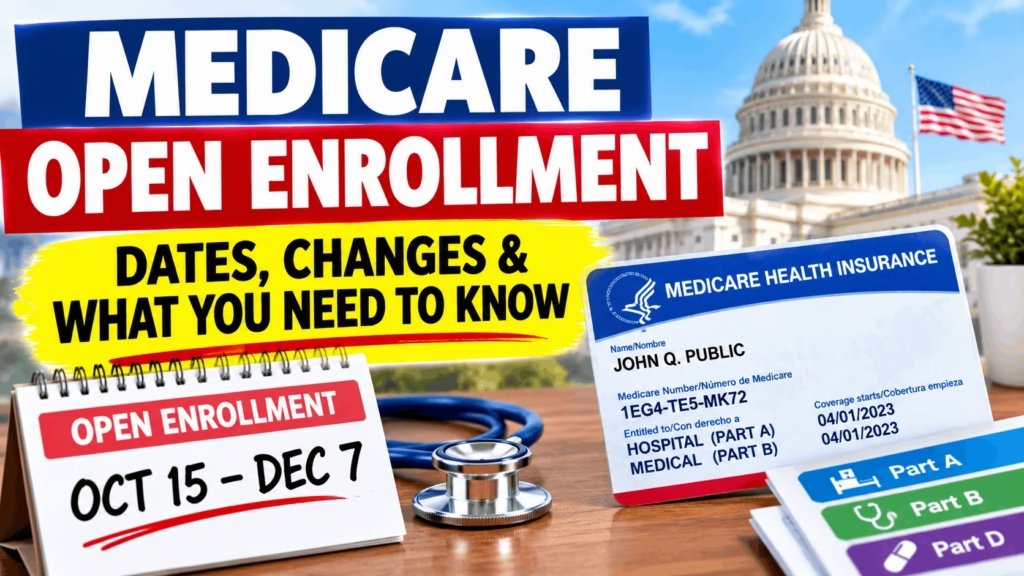
Medicare Open Enrollment Changes: Medicare open enrollment opens this Thursday, October 15, and the plan landscape that greets 34 million expected Medicare Advantage members looks different from last year’s. CMS said on September 28 that the average Medicare Advantage premium for 2027 will fall to $12 a month from $14.37, a 16.5 percent drop, while stand-alone drug plans edge up to an average of $36 from $35.09. Behind those friendly averages sits a quieter story. The typical beneficiary can now choose from 35 Medicare Advantage plans, down from 39 last year, according to KFF analysis relayed by the Medicare Rights Center, and insurers such as Humana have dropped plans that covered roughly 600,000 people. The window for choosing coverage that starts January 1 closes on December 7. We’ll be updating this article monthly.
If a nonrenewal notice or an Annual Notice of Change landed in your mailbox in the past two weeks, treat it as a deadline, not junk mail. CMS says about eight in 10 Medicare Advantage members can keep their current plan at the same or a lower premium, which also means roughly two in 10 cannot. Florida, Ohio and Illinois lose dozens of plans, and Wyoming loses nearly half of its options. Original Medicare users face their own Medicare open enrollment decisions because the Part D cap rises to $2,400 and the deductible climbs to $700. This guide explains the dates, the numbers and the practical steps, and it includes a free calculator that compares up to three plans by expected yearly cost.
Medicare Open Enrollment Changes 2026 Dates: Key Deadlines
| Date | What it means |
|---|---|
| September 28, 2026 | CMS announced 2027 Medicare Advantage and Part D premium averages |
| September 30, 2026 | Plans were required to send the Annual Notice of Change |
| October 2, 2026 | Deadline for plans to send nonrenewal notices to affected members |
| October 15, 2026 | Medicare open enrollment begins |
| December 7, 2026 | Medicare open enrollment ends |
| December 8, 2026 to end of February 2027 | Special enrollment period for people whose plan is leaving their area |
| January 1, 2027 | New plan coverage begins |
| January 1 to March 31, 2027 | Medicare Advantage open enrollment for people already in a Medicare Advantage plan, with limited changes allowed |
Most people use the Medicare open enrollment window between October 15 and December 7 to make changes. If you do nothing, you generally stay in your current plan, but the plan may carry new premiums, deductibles, networks and drug lists.
What Is Changing in Medicare Advantage for 2027?
CMS describes the market as stable, and the headline numbers support that picture. Medicare Advantage enrollment is projected at about 34 million people, or 47.4 percent of everyone with Medicare. The number of plans nationwide is essentially flat at about 5,532, compared with 5,553 in 2026. More than 99 percent of beneficiaries can reach at least one Medicare Advantage plan, and 97 percent can pick from 10 or more.
| Measure | 2026 | 2027 |
|---|---|---|
| Average monthly Medicare Advantage premium | $14.37 | $12.00 |
| Average Part D premium inside Medicare Advantage plans | $11.32 | $7.00 |
| Average stand-alone Part D premium | $35.09 | $36.00 |
| Total Medicare Advantage plans nationwide | 5,553 | about 5,532 |
| Average Medicare Advantage plans available per person (KFF) | 39 | 35 |
| Projected Medicare Advantage enrollment | n/a | about 34 million |
A lower average premium does not guarantee a lower bill for you. Averages are weighted by enrollment, so a handful of large plans pull the figure down. Individual plans can still raise deductibles, shrink dental allowances or tighten networks. One commentary based on the CMS landscape files argues that higher deductibles and out-of-pocket limits are showing up in continuing plans in the general market and that dental and Part B giveback amounts are noticeably smaller, though it gives no dollar figures, so treat that as an analyst’s reading rather than an official finding.
Breaking: Official 2027 COLA Time, What to Expect and Medicare Open Enrollment Checklist
2027 Social Security COLA Forecast: Latest 3.6% Estimate and How Much Retirees Could Get
Which States Are Losing the Most Medicare Advantage Plans?
Plan choice shrinks in 29 of 51 jurisdictions, counting the District of Columbia. The pattern is uneven, and it matters because a sharp drop in options often means fewer insurers competing for your business.
| State or area | Plans in 2026 | Plans in 2027 |
|---|---|---|
| Florida | 611 | 560 |
| Ohio | 212 | 180 |
| Illinois | 157 | 136 |
| Wyoming | 14 | 8 |
| Maryland and Washington, D.C. | about a quarter fewer plans | about a quarter fewer plans |
Wyoming’s loss of 43 percent is the largest in percentage terms, while Florida’s 51-plan decline is the largest by count, according to reporting from Medical Daily. One analysis of the CMS files also claims the number of counties with no Medicare Advantage plan rises from 67 to 181. We could not confirm that county count on a CMS page, so consider it unverified until an official source repeats it.
Is My Medicare Advantage Plan Ending? What to Do Right Now
Some of the biggest shifts come from insurer exits rather than from averages. Humana’s departures touch about 600,000 members, and the same commentary estimates that UnitedHealthcare’s affect 400,000 to 500,000 and CVS Aetna’s about 300,000. These are estimates, not CMS figures. The same analysis says at least 3.2 million people, about 10 percent of enrollees, must pick new coverage after a termination, and that another 2.1 million were moved to a different plan.
If you got a nonrenewal letter, take four steps. First, read the letter to see whether the insurer is offering a replacement plan, because some members are moved automatically. Second, do not assume the replacement keeps your doctors or drugs. Third, use open enrollment to compare it against other plans. Fourth, remember that people whose plan leaves their area get a special enrollment period from December 8 through the end of February 2027, so you are not out of options on December 8, although waiting leaves less time to fix problems.
Original Medicare with a Medigap policy follows different rules. If your Medicare Advantage plan leaves your area, you may have guaranteed access to certain Medigap plans, with a window that starts 60 days before coverage ends and runs 63 days after. Outside that situation, an insurer in most states can ask health questions before selling you a supplement.
Medicare Part D in 2027: Premiums, Deductible and the New Cap
Drug coverage is where many Original Medicare users feel the changes. The standard deductible rises to $700 from $615, and the out-of-pocket cap on covered drugs rises to $2,400 from $2,100. After you hit the cap, you pay nothing more for covered drugs for the rest of the year.
| Part D measure | 2026 | 2027 |
|---|---|---|
| Standard deductible | $615 | $700 |
| Out-of-pocket cap | $2,100 | $2,400 |
| Average stand-alone premium | $35.09 | $36.00 |
| Basic plan at $10.30 or less | n/a | available to 88 percent of non-low-income beneficiaries |
| Enhanced plan under $6 | n/a | available to 93 percent of non-low-income beneficiaries |
The Part D Premium Stabilization Demonstration ends after 2026. According to one analysis, it trimmed the base premium by $15 in 2025 and $10 in 2026 and cost about $9.8 billion over two years. CMS has said the Part D market shows broad pricing stability, but KFF has warned that without the subsidies some stand-alone plan members could face larger increases than in recent years. The same commentary says no zero-premium stand-alone plans will be available to people without low-income help, which would mean about 4 million people who paid nothing in 2026 will pay something in 2027. Rising drug prices and heavier use of GLP-1 and other specialty drugs add pressure.
If you take a specialty drug, a $0 premium can be a trap. Look at the tier your medication sits on, any prior authorization rules and the pharmacy network before you look at the monthly price.
Original Medicare vs Medicare Advantage: Which Fits You in 2027?
There is no universal winner. The right answer depends on your health, your doctors and how much risk you are willing to carry.
| Feature | Original Medicare with Part D and Medigap | Medicare Advantage |
|---|---|---|
| Doctor choice | Any provider that accepts Medicare | Plan network, with prior authorization common |
| Yearly out-of-pocket cap | None for Original Medicare alone; Medigap can limit exposure | Required cap on in-network costs |
| Monthly premium | Part B plus Part D plus Medigap | Part B plus plan premium, often low or $0 |
| Extra benefits | Usually none unless added | Often dental, vision, hearing, over-the-counter allowances |
| Switching rules | Medigap underwriting may apply | Annual switching, with limited changes in early months |
| Travel coverage | Nationwide | Depends on plan and network |
A plan with a $0 premium is not free, because you still pay the Part B premium, and you pay copays when you use care. If you rarely use services, a lean plan can win. If you expect surgery, specialist visits or frequent hospital stays, a higher premium with a lower cap may cost less overall.
2027 Social Security COLA Forecast: Latest 3.6% Estimate and How Much Retirees Could Get
Medicare Plan Cost Calculator: Compare Up to Three Plans
The calculator below helps you compare expected yearly costs for up to three options. You enter each plan’s monthly premium, deductible, the medical costs you expect to pay and your estimated drug costs. It applies the $2,400 Part D cap automatically, shows your best case and your worst case, and highlights the lowest expected cost. Nothing is stored or sent. It is an estimate, not a quote, and your plan documents control the real numbers.
Medicare Plan Cost Calculator: Compare 2027 Coverage
Compare up to three options by expected and worst-case yearly cost. Nothing is stored or sent.
Option 1
Option 2
Option 3 (optional)
Estimate only. Drug costs are capped at the 2027 Part D out-of-pocket limit of $2,400. Medical out-of-pocket costs are capped at the limit you enter, and an option with no limit shows the worst case as unlimited. Part B figures are Medicare Trustees estimates until CMS publishes the official 2027 premium. Check each plan’s Evidence of Coverage and the Medicare Plan Finder for real numbers.
Should You Switch During Medicare Open Enrollment? Five Warning Signs
Staying put is a legitimate choice, but a few signals suggest the annual review deserves real effort. Your doctor or hospital is leaving the plan's network. A medication you take moved to a higher tier or now needs prior authorization. Your deductible or out-of-pocket limit rose noticeably in the Annual Notice of Change. Your plan dropped dental, vision or over-the-counter benefits that you actually use. Or your health changed, so the expected cost of care this year looks nothing like last year's. Any one of these is a reason to run the numbers in the calculator above before the Medicare open enrollment window shuts on December 7.
Medicare Part B in 2027: What We Know and What We Don't
CMS has not yet published the official 2027 standard Part B premium or deductible. The Medicare Trustees' estimate points to a premium of $209.50, up $6.60 from $202.90, and a deductible of $292, up from $283. Because Part B is usually deducted from Social Security payments, the final number can change how much of your cost-of-living raise you keep. We will update the figures here when CMS confirms them.
Medicare Open Enrollment Scams: How to Protect Yourself
Open enrollment brings a spike in aggressive marketing. Be wary of anyone who calls you unprompted about Medicare benefits, offers gifts for switching plans, asks for your Medicare number over the phone or says your card is about to expire. Real plans do not need your Social Security number to give you a quote. Hang up, then call 1-800-MEDICARE yourself or contact your State Health Insurance Assistance Program for free, unbiased help. If you work with a licensed broker, ask which companies they represent and confirm your doctors and drugs against the plan's own documents before you sign.
How to Switch Medicare Plans?
You can change plans without cancelling the old one, because enrolling in a new plan ends the old one automatically.
- Gather your plan documents. Pull your Annual Notice of Change, your list of drugs with doses, and your doctors' names.
- Open the Medicare Plan Finder. CMS says it is adding preventive service details, direct links to drug lists and plan summaries, and alerts about changes affecting your current plan.
- Compare total costs. Add the premium, deductible, copays and the cap, not just the monthly price.
- Confirm networks. Call your doctors and your pharmacy and ask whether they will be in network next year.
- Enroll. You can enroll online through the Plan Finder, by phone through 1-800-MEDICARE or directly with the insurer.
- Save proof. Keep the confirmation number, and if you enroll by phone, write down the date, time and agent's name.
Medicare Processing Time: When Does New Coverage Start?
Choices made by December 7 take effect on January 1, 2027. If you make more than one choice, the last one made before the deadline generally counts. Plans usually mail a welcome packet and a member card within a few weeks of enrollment. If nothing arrives by late December, call the plan, because a missing card in January is harder to fix than one missing in December. People whose plan is ending have extra time under the special enrollment period, but coverage gaps are possible if you wait.
Medicare Payment Schedule: How and When You Pay Premiums
Premiums for 2027 begin with January coverage. Part B is usually taken out of a Social Security or Railroad Retirement payment, and people who do not receive those payments are billed directly. Medicare Advantage and stand-alone Part D premiums can be paid to the plan or, in many cases, deducted from your monthly Social Security check, though the first deduction can take a couple of months to start and early bills may be larger to catch up. Check the first statement against your plan documents to make sure the premium matches what you agreed to.
Extra Help and Medicare Savings Programs: Don't Skip This Step
Many eligible people are not enrolled in Extra Help, the Part D low-income subsidy, or in the Medicare Savings Programs that can pay your Part B premium. Medicare Rights Center and Justice in Aging both point to these programs as a major source of savings. Eligibility depends on income and resources, and states set some of the rules, so ask your SHIP counselor to screen you. The Medicare Rights helpline is 800-333-4114, and 1-800-MEDICARE operates around the clock.
SNAP Work Requirements: Who Is Affected, Ages 18 to 64, Exemptions and Calculator
Official Medicare Resources and Application Links
| Resource | Use it for | Link |
|---|---|---|
| Medicare Plan Finder | Compare Medicare Advantage and Part D plans | https://www.medicare.gov/plan-compare |
| Medicare account login | View claims, coverage and your Medicare card | https://www.medicare.gov/account/login |
| Medicare.gov | Costs, coverage and enrollment rules | https://www.medicare.gov |
| 1-800-MEDICARE | Enrollment help by phone, 24 hours a day | 1-800-633-4227 |
| State Health Insurance Assistance Programs | Free, local, unbiased counseling | https://www.shiphelp.org |
| Extra Help application | Apply for the Part D low-income subsidy | https://www.ssa.gov/medicare/part-d-extra-help |
| Social Security enrollment | Sign up for Medicare Part A and Part B | https://www.ssa.gov/medicare |
| CMS newsroom | Official announcements and press releases | https://www.cms.gov/newsroom |
| Medicare Rights Center | Independent consumer help and helpline | https://www.medicarerights.org |
FAQs About Medicare Open Enrollment
When is Medicare open enrollment in 2026?
Medicare open enrollment runs from October 15 to December 7, 2026. Coverage you choose begins on January 1, 2027.
Do I have to re-enroll in Medicare every year?
No. You stay in your plan unless you change it, but your plan may change its costs, networks and drug list, so review it each fall.
What happens if I miss Medicare open enrollment?
You generally stay in your current coverage. Some people qualify for a special enrollment period, such as those whose plan is leaving their area, and Medicare Advantage members have a limited window from January 1 to March 31.
Why is my Medicare Advantage plan ending?
Insurers choose each year which plans to offer. Rising costs have led several large carriers to exit counties or discontinue products, and CMS says about two in 10 Medicare Advantage members cannot keep their current plan at the same or lower premium.
What is the Part D out-of-pocket cap for 2027?
The cap is $2,400, up from $2,100, and the standard deductible is $700.
How much will Medicare Part B cost in 2027?
The official number is not yet announced. The Trustees' estimate is $209.50 a month.
Can I switch from Medicare Advantage to Original Medicare?
Yes, during open enrollment. You would also add a stand-alone Part D plan, and you should check whether you can get a Medigap policy, since insurers in most states may use medical underwriting.
Where can I get free help choosing a plan?
Your State Health Insurance Assistance Program offers free, unbiased counseling, and 1-800-MEDICARE is available 24 hours a day.
Can I change my Medicare Advantage plan any time?
Not any time. You can change during open enrollment, during the January 1 to March 31 Medicare Advantage window with limits, or when a special enrollment period applies.
What is the difference between Medicare open enrollment and Medicare Advantage open enrollment?
The first runs October 15 to December 7 and allows broad changes. The second runs January 1 to March 31 and is limited to people already in a Medicare Advantage plan.
Is a $0 premium Medicare Advantage plan really free?
No. You still pay the Part B premium, and copays, deductibles or drug costs can add up.
What is the average Medicare Advantage premium in 2027?
About $12 a month, down from $14.37, according to CMS.
Conclusion
Medicare open enrollment is less about one big new rule and more about many small shifts that add up. Average Medicare Advantage premiums are lower, but some plans have disappeared, deductibles and limits are creeping up in places, and Part D has a higher cap and no extra subsidy cushion. The best defense is simple. Read the notice you received, list your doctors and drugs, compare the total yearly cost of at least three options, and confirm networks by phone. If your plan is ending, use the extra enrollment time but do not wait for it. Finish your choice before December 7 and save your confirmation. Check back for updates when CMS publishes the official 2027 Part B premium.
Is Your 2027 COLA Eaten by Medicare Premiums? What You Really Keep After Part B
Social Security COLA 2027 by State: These 10 States Could See the Biggest Dollar Increase