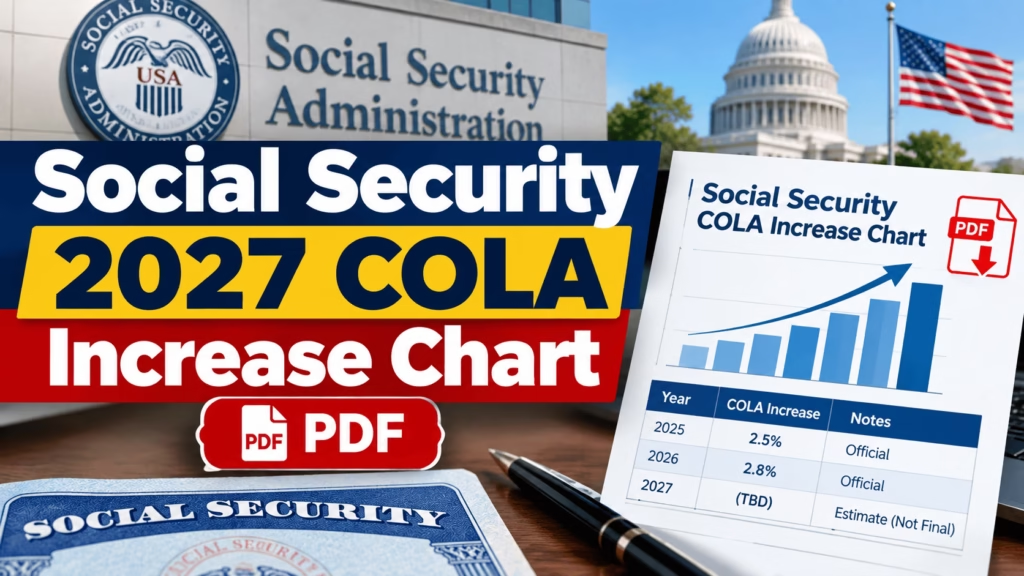
Social Security 2027 COLA Increase Chart PDF: The Social Security COLA increase for 2027 is now days from being official. The Social Security Administration (SSA) is scheduled to announce the new cost-of-living adjustment on October 14, 2026, the same morning the Bureau of Labor Statistics (BLS) publishes the September inflation report. Most forecasters expect a figure between 3.4% and 3.6%. That would be the biggest raise for retirees, disabled workers and survivors in several years and well above the 2.8% they received in 2026.
The estimates come from three well-known trackers. AARP projects 3.6%, based on August inflation data. The Senior Citizens League (TSCL) published its final forecast of 3.5% after the August report, and independent analyst Mary Johnson has also pointed to roughly 3.5%. The Committee for a Responsible Federal Budget sits slightly lower at 3.4%. For the average retired worker, that range works out to roughly $66 to $75 more per month. The gap between the forecasts is small because two of the three inflation months that decide the final number are already published. Nothing is final until SSA says so. A hotter or cooler September could nudge the rate a tenth of a point in either direction, which is why every estimate in this article is labelled as a projection. We’ll be updating this article monthly, and we will refresh the numbers again as soon as the official announcement is out.
Social Security 2027 COLA Increase Chart PDF Key Dates and Highlights
| Item | Latest detail |
|---|---|
| Official COLA announcement | October 14, 2026 |
| Final inflation report used | September 2026 CPI-W, released October 14 |
| July 2026 CPI-W | 327.104 (up 3.4% from a year earlier) |
| August 2026 CPI-W | 328.481 (up 3.5% from a year earlier) |
| AARP estimate | 3.6% |
| TSCL final estimate | 3.5% |
| CRFB estimate | 3.4% |
| 2026 COLA for comparison | 2.8% |
| First check with the raise | January 2027 benefits (SSI raise arrives with the payment issued in late December) |
| People affected | About 71 million Social Security and SSI recipients |
What Is the Social Security COLA and How Is It Calculated?
COLA stands for cost-of-living adjustment. It is the yearly increase that tries to keep Social Security and Supplemental Security Income (SSI) payments from losing buying power as prices climb. Congress built the system into law in the 1970s, and since 1975 the raise has been automatic. Nobody has to apply for it.
The formula is simple to describe. SSA takes the average of the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W) for July, August and September. It then compares that average with the same three-month average from the previous year. The percentage difference, rounded to the nearest tenth, becomes the COLA. If the average rises 3.5%, the COLA is 3.5%. If prices fall, the benefit stays the same, because the law does not allow a cut through this mechanism.
Two details trip people up. First, the index used is CPI-W, which tracks the spending of working households, not the broader CPI-U that dominates headlines. Second, only the third quarter matters. A price spike in March has no direct effect on the number, though it can pull the quarterly average up if it lingers.
GOP Convention Fact-Check: What Held Up and What Didn’t From the Dallas Midterm Convention
How Much Will My Social Security Check Increase in 2027?
The honest answer is that it depends on your current benefit and the final percentage. The calculation is a straight multiplication. Take your monthly benefit before Medicare deductions and multiply by the COLA rate. The table below uses a 3.5% rate, which sits in the middle of the current forecasts.
| Current monthly benefit | Increase at 3.5% | New monthly benefit |
|---|---|---|
| $1,000 | $35.00 | $1,035.00 |
| $1,500 | $52.50 | $1,552.50 |
| $1,937.53 (average retired worker) | $67.81 | $2,005.34 |
| $2,500 | $87.50 | $2,587.50 |
| $3,000 | $105.00 | $3,105.00 |
| $4,000 | $140.00 | $4,140.00 |
TSCL’s own example uses its earlier 3.6% projection. At that rate, an average benefit of $1,937.53 would climb by $69.75 to $2,007.28. AARP’s math lands a bit higher, at about $75 more per month for the typical retired worker, because it uses a slightly different average benefit base. Use the calculator file that comes with this article, social-security-cola-calculator.html, to run your own number in seconds.
Remember that the figure you see in your bank account will usually be smaller than the gross raise. Medicare Part B premiums come out of most checks, and those premiums normally rise each year too. The 2027 Part B amount has not been announced yet, so the net effect is something to check once the Medicare trustees and the Centers for Medicare & Medicaid Services publish it.
Social Security 2027 COLA Increase Chart PDF and Calculator
You can drop the calculator into your page as an HTML block. It asks for the current monthly benefit, offers the three leading estimates plus a custom field for the official rate, and returns the monthly raise, the new payment and the extra income over twelve months. Once SSA announces the real figure on October 14, type it into the custom box. Embed the code from the file named above, and the tool needs no outside scripts, so it will not slow your page.
Social Security 2027 COLA Increase Chart PDF and Calculator
Official COLA expected from SSA on October 14, 2026. Figures below are estimates until then.
Your 2027 result
| COLA rate used | – |
| Monthly increase | – |
| New monthly benefit (January 2027) | – |
| Extra income over 12 months | – |
COLA increase chart by benefit amount
| Current benefit | Monthly raise | New benefit |
|---|
Social Security COLA history chart
Estimates only, before Medicare Part B and other deductions. Source for history and announcement date: Social Security Administration (ssa.gov/oact/cola). To save a PDF, choose “Save as PDF” in the print window.
Why the 2027 COLA Looks Bigger Than Last Year
The 2026 raise was 2.8%, the 2025 raise was 2.5%, and the 2024 raise was 3.2%. A 3.5% reading would be the highest since 2023, when beneficiaries received 8.7% after the inflation surge that followed the pandemic. Here is the recent history in one place.
| Year | COLA |
|---|---|
| 2022 (applied to benefits for 2023) | 8.7% |
| 2023 (applied to benefits for 2024) | 3.2% |
| 2024 (applied to benefits for 2025) | 2.5% |
| 2025 (applied to benefits for 2026) | 2.8% |
| 2026 (applied to benefits for 2027) | Expected 3.4% to 3.6% |
Note: SSA names each raise for the year it takes effect, so the “2027 COLA” is the one calculated this fall and paid starting in January 2027.
Why is inflation running hotter this year? Energy is the biggest piece. The August report showed gasoline up 3.9% in a single month and about 27% higher than a year earlier, and fuel alone accounted for more than a third of the monthly increase in overall prices. Analysts also point to higher food and housing costs, and to global tensions that have pushed up energy markets. For retirees, those categories take up a bigger share of the budget, which is why many older Americans say the official CPI-W understates what they feel at the pump and the grocery store.
Latest Estimates From AARP, TSCL and Other Forecasters
AARP updated its projection to 3.6% after the August inflation report, up from 3.5% the month before. Its method uses actual CPI-W data from October 2025 through August 2026 and the Federal Reserve Bank of Cleveland’s projection for September.
TSCL has moved around more. Earlier in the year it projected as low as 2.5%, then climbed to 3.8% over the summer, then eased to 3.6% and finally 3.5% as the actual monthly data came in. That swing is a useful reminder that early-year estimates are guesses, while late-season estimates are mostly arithmetic.
The Committee for a Responsible Federal Budget shows 3.4%, the low end of the range. The group has also proposed changes to how COLAs work, including limiting raises for higher-income beneficiaries, though no such change has been enacted.
The takeaway for planning is a range, not a point. A reasonable assumption is a raise of 3.4% to 3.6%, with the exact number confirmed on October 14.
When Will the 2027 COLA Be Announced?
SSA plans to publish the figure on October 14, 2026, the same day the BLS releases the September CPI. That is back to the normal mid-October rhythm. Last year was different. A federal government shutdown delayed the September 2025 inflation report, and the 2026 COLA announcement, originally set for October 15, slipped to October 24, 2025. A shutdown also wiped out the October 2025 CPI reading completely.
If you want the first word, watch SSA’s newsroom and its press release page on the morning of the 14th. Notices to individual beneficiaries follow later. People with a my Social Security account can see their new benefit amount online in early December, and paper notices usually arrive in December as well.
SSI Payment Gap Alert: 2 Deposits in October, None in November, 2 in December (Full Calendar)
Social Security COLA 2027 for Seniors Could Get Nearly $200 More Per Month
Social Security Payment Schedule for January 2027
The first check with the raise is the one that covers January 2027 benefits. When it lands depends on how you qualify and, for many people, your birthday. The calendar for the month below is based on SSA’s standard rules, so confirm your own date in your account.
| Group | Payment date for January 2027 benefits |
|---|---|
| Started benefits before May 1997, or get both Social Security and SSI | The 3rd of the month falls on a Sunday, so the payment generally goes out on the last business day before, which is expected to be December 31, 2026 |
| Birthday on the 1st to 10th | Second Wednesday, January 13, 2027 |
| Birthday on the 11th to 20th | Third Wednesday, January 20, 2027 |
| Birthday on the 21st to 31st | Fourth Wednesday, January 27, 2027 |
| SSI recipients | Normally the 1st; because January 1 is a holiday, payment is expected on December 31, 2026 |
Two points worth knowing. People who receive both Social Security and SSI will see two different COLA effects, since both programs use the same percentage but SSI is a smaller payment with different rules. And if you collect on a family member’s record, the payment day follows the rules for your category, not the worker’s.
Payment Dates in Context: What Changes and What Doesn’t
Even with the raise, some pieces of Social Security get adjusted at the same time and are worth watching. The taxable earnings cap, the earnings test thresholds for people who claim before full retirement age, and the amount you need to earn for a work credit are all indexed to national average wage growth, and SSA publishes them with the COLA announcement. For reference, the 2026 taxable maximum is $184,500 and the 2026 earnings test limit for people under full retirement age all year is $24,480. The 2027 versions had not been published at the time of writing.
That also means a larger COLA does not help everyone equally. Higher earners may see more of their income subject to payroll tax, and some beneficiaries may see more of their Social Security become taxable, because the federal income thresholds for taxing benefits ($25,000 for single filers, $32,000 for joint filers at the first tier) are not indexed to inflation. A bigger raise can push more people over those lines.
How to Apply: Do You Need to Do Anything to Get the COLA?
No application is required. The increase is automatic for everyone already getting Social Security retirement, survivor or disability benefits, and for SSI recipients. If you are about to start benefits, the COLA gets built into your amount once you are on the rolls, and benefits you have not yet claimed still grow with COLAs from the year you turn 62.
What you should do is make sure your information is current so the raise reaches the right account. Here is a short checklist.
- Create or sign in to your my Social Security account and confirm your mailing address, phone number and direct deposit details.
- Choose paperless notices if you want your COLA letter in your online message center instead of the mail.
- Check your Medicare premium once CMS publishes the 2027 rates, so you can estimate the net raise.
- If you plan to claim soon, use SSA’s retirement estimator to see how the new COLA changes your projected amount.
For people who need to start a claim, the process runs through SSA’s website, by phone at 1-800-772-1213, or at a local office by appointment. Retirement claims can be filed online up to four months before you want benefits to start.
Processing Time: How Long Until the Raise Appears?
Because the COLA is automatic, there is no processing queue for the raise itself. SSA updates the payment amounts in its systems after the announcement and sends notices over the following weeks. The first payment at the higher amount is the January 2027 payment described above. If you filed a new retirement or disability claim recently, that is a different matter. Retirement applications often take roughly one to three months. Disability claims commonly take several months for an initial decision, and appeals take longer. A new claim does not change how the COLA is applied, only when your first payment starts.
If your notice shows an amount that looks wrong, check whether the Medicare premium, a withholding for federal tax, or a repayment of an old overpayment is reducing the deposit. Those deductions explain most confusion about “missing” raises.
Medicare Part B and the Net Raise
The Part B standard monthly premium was $202.90 in 2026. It has typically risen every year, and the 2027 amount will arrive later in the fall. When the premium rises, your net raise shrinks. For many people the “hold harmless” rule protects the Social Security check from dropping because of a Part B increase, but that protection does not guarantee a full raise. Anyone paying income-related surcharges (IRMAA) should also watch the thresholds, since a higher COLA can push total income into a higher tier in a later year.
No SSI Payment in November 2026? Why October and December Pay Twice
Who Gets 3 Deposits in October 2026? SSI + Social Security Recipients Explained
What a 3.5% Raise Means for Retirement Budgets
A percentage can sound bigger than it feels. A $70 monthly raise sounds helpful, but many retirees have already seen bills rise by more than that. TSCL’s 2026 survey found that about 44% of older Americans, roughly 24.8 million people, now rely on Social Security as their only source of retirement income, up from 39% a year earlier. Those households do not have a cushion to absorb a cost spike.
Here are practical ways to use the news. Look at your biggest recurring costs first, especially housing, utilities, insurance and prescriptions. Review your Medicare Advantage or Part D plan during open enrollment, which runs from October 15 to December 7, since a plan change can matter more than a COLA tenth of a point. Ask your pharmacist about lower-cost options and check whether you qualify for state assistance programs, property tax relief or utility discounts. And if you are still working and thinking about claiming, remember that each year you delay between 62 and 70 raises your monthly benefit, on top of any COLA.
Why Seniors Say CPI-W Does Not Capture Their Costs
Advocates have argued for years that CPI-W is a poor fit for older adults. The index weights spending by working households, where wages, transportation and clothing matter more. An experimental index called CPI-E, built around households headed by someone 62 or older, gives more weight to health care and housing. Over long periods, CPI-E has often risen a bit faster than CPI-W, though not every year. Bills to switch Social Security to CPI-E have been introduced repeatedly in Congress and have not become law.
At the same time, some budget groups argue for slower growth in COLAs to help the program’s finances. The most recent trustees’ projections warn that the combined retirement and disability trust funds face a funding shortfall in the 2030s unless Congress acts, and that benefits could be cut by roughly a fifth after that point if nothing changes. That is a long-term policy debate and has no effect on the 2027 raise, which is set by formula, but it explains why every COLA discussion in Washington carries a second conversation about solvency.
SSI and VA Benefits: Who Else Gets the Raise?
The same percentage applies to SSI, which supports people with limited income and resources who are aged, blind or disabled. The federal SSI payment amounts rise with the Social Security COLA, and states that add their own supplement may handle it differently. Federal civil service retirees under CSRS receive the same COLA as Social Security, while those under FERS generally get a reduced version when inflation is above 2%. With a 3.5% base, observers expect a FERS COLA near 2.5%. Veterans who receive VA disability compensation have their own COLA, which by law matches the Social Security percentage, and that is usually confirmed shortly after the SSA announcement.
Official Websites and Resources
| Resource | What you can do | Link |
|---|---|---|
| Social Security Administration | News, COLA announcement, benefit information | https://www.ssa.gov |
| COLA information page | Past COLAs and how they are calculated | https://www.ssa.gov/oact/cola/ |
| my Social Security login | View statements, benefit letters, update direct deposit | https://www.ssa.gov/myaccount/ |
| Apply for retirement benefits | Start an online retirement claim | https://www.ssa.gov/apply/retire |
| Apply for disability benefits | File a disability claim | https://www.ssa.gov/benefits/disability/ |
| Check application status | Look up the status of a claim | https://www.ssa.gov/myaccount/ |
| Payment schedule | Check your monthly payment date | https://www.ssa.gov/benefits/retirement/planner/paymentdates.html |
| Bureau of Labor Statistics CPI | Official inflation data and release schedule | https://www.bls.gov/cpi/ |
| Medicare | Premiums, plans and open enrollment | https://www.medicare.gov |
| Senior Citizens League | Monthly COLA estimates | https://seniorsleague.org |
| AARP COLA estimate | Inflation-based projection and explainer | https://www.aarp.org/social-security/ |
What to Watch Before and After October 14
Three things matter in the next few weeks. The September CPI-W reading will lock the final percentage. Medicare’s 2027 premium announcements will show how much of the raise stays in your pocket. And the SSA release will include the new taxable maximum and earnings test limits, which matter for anyone still working or planning to claim early.
If you are building a budget, treat 3.5% as the planning figure, set aside the possibility of a rate a tenth or two on either side, and wait for the official release before making a decision that depends on the exact amount.
Conclusion
The Social Security COLA increase for 2027 looks set to land around 3.5%, which would mean roughly $65 to $75 more each month for the average retired worker. It is the biggest raise in several years, driven mainly by higher fuel and living costs, but it will not erase the squeeze many older households feel. Medicare premiums, taxes and everyday prices will shape how much of the raise you keep. The official announcement arrives on October 14, 2026, and the higher payments begin with January 2027 benefits. Use the calculator, check your my Social Security account, and come back after the announcement, because we’ll be updating this article monthly as new numbers arrive.
FAQs About Social Security 2027 COLA Increase Chart PDF
What is the Social Security COLA increase for 2027?
The official number has not been released yet. SSA will announce it on October 14, 2026. Current forecasts from AARP, TSCL and independent analysts range from 3.4% to 3.6%, with 3.5% the most common estimate.
When will Social Security checks go up in 2027?
The higher amount shows up in the payment for January 2027 benefits. SSI recipients typically see it with the payment issued at the end of December 2026 for January, because the first of the month is a holiday.
How much will the average retiree get?
Using the average retired worker benefit of $1,937.53 cited by TSCL, a 3.5% raise adds about $67.81 a month, while 3.6% adds about $69.75. AARP’s estimate for the typical retired worker is about $75 a month.
Do I have to apply for the COLA?
No. The raise is automatic for current beneficiaries. You only need to keep your contact and bank information up to date.
Is the 3.5% figure guaranteed?
No. The final figure depends on September inflation. Two of the three months used in the formula are known, but September can shift the result by a tenth of a point or so.
Will Medicare take away part of my raise?
Probably some of it. Most beneficiaries pay the Part B premium from their Social Security check, and that premium usually rises each year. The 2027 amount will be announced later this fall.
Is the 2027 COLA higher than last year?
If the forecasts are right, yes. The 2026 COLA was 2.8%, so a 3.5% raise would be about seven tenths of a point higher.
What happens if inflation goes down?
If the third-quarter average does not exceed last year’s, the COLA is zero and benefits stay the same. That has happened only a handful of times, and a zero COLA is not expected this year.
Will Social Security get a 5% raise in 2027?
There is no sign of one. The data through August support a range near 3.5%, and a figure as high as 5% would need a very large jump in September prices.
Why was the COLA announcement late last year?
A federal government shutdown delayed the September 2025 CPI release, so the announcement moved from October 15 to October 24, 2025. This year the schedule is back to October 14.
How is the COLA calculated for Social Security?
SSA averages CPI-W for July, August and September, compares it with the same period a year earlier, and rounds the percentage change to one decimal place.
Do SSDI and SSI recipients get the same COLA?
Yes. Social Security retirement, survivor and disability benefits and SSI all use the same percentage.
Will my Social Security be taxed more after the COLA?
It can be. The income thresholds that decide whether your benefits are taxable are not adjusted for inflation, so a larger raise can move some households into taxable territory.
When can I see my new benefit amount?
Most people can find it in their my Social Security account in early December, and SSA mails notices around the same time.
Does the COLA apply if I have not started benefits yet?
Yes. If you are 62 or older and not yet collecting, your future benefit still reflects the COLAs that applied from the year you turned 62.
$90 Medicare Improvement Fund Rebate Check: Who Gets It, Eligibility and Payment Date
2027 Medicare Part B Premium Announced: Will It Cancel Your COLA?