By GovtSchemes.org Editorial Team | Last updated: October 21, 2026
Canada Mandatory Retirement at 65: A claim keeps circulating online that Canada abolished mandatory retirement at 65 in November 2025. It did not. Forced retirement based on age alone was dismantled years earlier, and the real news for retirees this autumn is something different: a 1.4% bump to Old Age Security (OAS) and the Guaranteed Income Supplement (GIS) arriving on October 28, new payment dates, and a pending announcement of the 2027 CPP earnings ceiling. This guide separates the recycled rumour from verified, current facts.
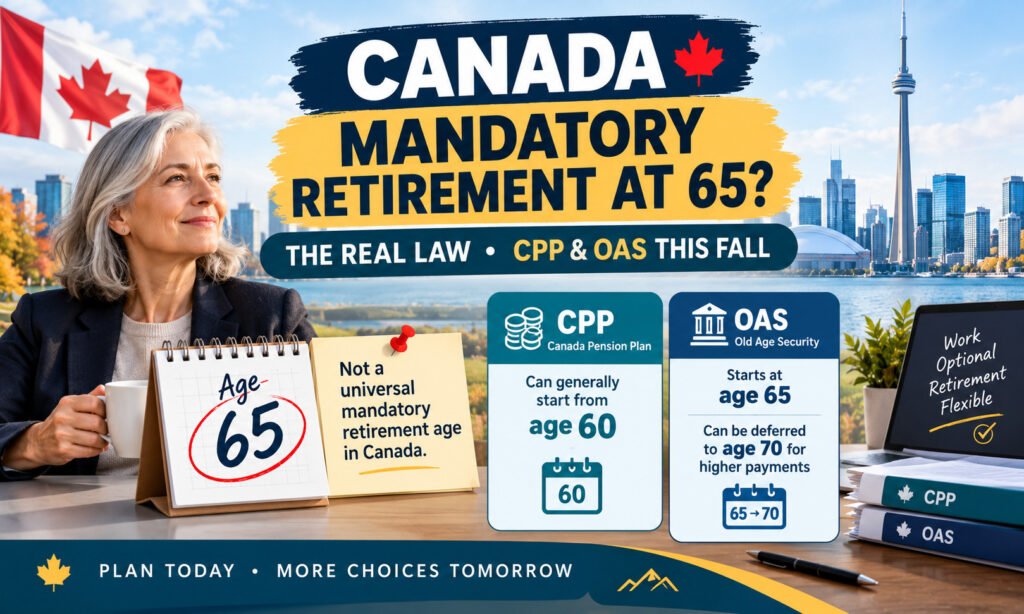
No employer in Canada can force you to retire at 65 simply because of your age, and that has been the case for over a decade. The only exceptions are narrow ones, where an employer proves that a specific age limit is a genuine job requirement. What does matter for your retirement date is when you choose to start the Canada Pension Plan (CPP, any time from 60 to 70) and OAS (from 65, deferrable to 70).
Key Figures at a Glance
| Item | Current figure |
| Is mandatory retirement at 65 legal in Canada? | No, not on the basis of age alone |
| Rumoured reform date (“November 2025”) | Not supported by any official announcement |
| Maximum new CPP retirement pension at 65 (2026) | $1,507.65 per month |
| OAS maximum, ages 65 to 74 (Oct to Dec 2026) | $762.50 per month |
| OAS maximum, ages 75 and over (Oct to Dec 2026) | $838.75 per month |
| Latest OAS and GIS increase | 1.4% from October 2026 |
| Next CPP and OAS payment | Wednesday, October 28, 2026 |
| OAS recovery tax (clawback) threshold, July 2026 to June 2027 | $93,454 (based on 2025 income) |
| OAS recovery tax threshold, July 2027 to June 2028 | $95,323 (based on 2026 income) |
Myth vs Fact: Did Canada End Mandatory Retirement in November 2025?
The myth: A sweeping federal reform took effect in November 2025 and freed Canadians from retiring at 65.
The fact: The legal groundwork was finished long before. Provinces moved first, and Ottawa followed for federally regulated workplaces such as banks, airlines and telecom companies. A law repealing the relevant parts of the Canadian Human Rights Act and the Canada Labour Code received Royal Assent on December 15, 2011, and took effect on December 15, 2012.
The rumour survives because it wraps a true message (you do not have to stop working at 65) inside a fake news hook. Whenever a post says a rule is brand new, check the date and the source before you act on it.
How Mandatory Retirement Actually Ended?
| Period | What happened |
| 2006 | Ontario removed the age-65 exception from its human rights framework |
| 2008 | British Columbia ended mandatory retirement, effective January 1 |
| Late 2011 | Every Canadian jurisdiction except New Brunswick had already abolished it |
| December 15, 2011 | Federal legislation repealing the permissive provisions received Royal Assent |
| December 15, 2012 | The federal repeal came into force, covering federally regulated employers |
One caveat: an employer may still defend an age-based rule if it can show the age is a genuine occupational requirement. Court and tribunal fights over airline pilots are the best-known example. Without that proof, forcing someone out because of age is treated as discrimination.
Trending Now: What Is Really Happening This Fall
1. OAS and GIS rise 1.4% on October 28
OAS is reviewed four times a year, in January, April, July and October, and it rises with the cost of living but never falls. The October review is the largest of 2026, lifting the 12-month increase to roughly 3%. The raise is applied automatically, so you do not need to apply or call anyone.
| Benefit (maximum monthly) | July to Sept 2026 | Oct to Dec 2026 |
| OAS, ages 65 to 74 | $751.97 | $762.50 |
| OAS, ages 75 and over | $827.17 | $838.75 |
| GIS, single, widowed or divorced | $1,123.17 | about $1,138.89 |
| GIS, partner receives full OAS | $676.09 | $685.56 |
The ages-75-and-over rate reflects a permanent 10% increase that starts automatically the month after your 75th birthday. Keep in mind that GIS is not taxable, while the OAS pension is.
2. Payment dates for the rest of 2026
| Month | CPP, OAS and GIS deposit date |
| October | Wednesday, October 28 |
| November | Thursday, November 26 |
| December | Tuesday, December 22 |
The December deposit lands early so it arrives before the holiday bank closures. Some third-party sites list different dates, so rely on the official government calendar linked below.
3. The 2027 CPP earnings ceiling is about to be announced
Every year the Canada Revenue Agency publishes the next year’s Year’s Maximum Pensionable Earnings (YMPE) and the matching contribution maximums. Last time around, the announcement for 2025 came on November 1, 2024, so workers and employers can expect the 2027 numbers in early November 2026. The 2026 YMPE is $74,600. Any 2027 figure you see before the official release is a projection, not a fact.
4. The viral “$1,508 CPP payment”
Headlines promoting a $1,508 CPP deposit are mixing up two things. $1,507.65 is the theoretical maximum for someone who started at 65 after contributing at or near the ceiling for nearly the whole contributory period. It is not a bonus, and it is not what the typical new retiree receives. Your own amount appears in your My Service Canada Account.
5. The clawback year confusion
Many articles mix up which income year goes with which threshold. The 2026 figure of $95,323 is the threshold applied to your 2026 income, and it affects OAS from July 2027 to June 2028. The amount currently being applied, from July 2026 to June 2027, is $93,454 and is based on your 2025 income. The October increase does not change either threshold.
CPP: Choosing Your Start Age
| Start age | Effect on monthly CPP |
| 60 | Reduced by 0.6% for each month before 65, up to 36% less, permanently |
| 65 | Standard amount |
| 70 | Increased by 0.7% for each month after 65, up to 42% more, for life |
For illustration, the 2026 maximum of $1,507.65 at 65 would grow to roughly $2,140 a month if started at 70 and assuming that same starting point. CPP also rose 2.0% in January 2026, and the January 2027 adjustment will follow inflation and has not been published yet. If you keep working while collecting, you can earn small additional lifetime top-ups called post-retirement benefits; the maximum new top-up in 2026 is $54.69 a month.
The CPP enhancement, which gradually raises the share of earnings the plan replaces, finished its legislated rate increases with 2025.
OAS: Eligibility and Deferral
- Age: 65 or older. OAS cannot start earlier, but it can be deferred.
- Residency: you generally need 10 years of residence in Canada after age 18 to receive a partial pension if you live in Canada, and 40 years for the full amount. Living abroad generally requires 20 years.
- Deferral: each month of delay adds 0.6%, up to 36% at age 70. Using the new October maximum, that works out to about $1,037 a month.
- Late applicants: if you apply after 65, retroactive payments can go back up to 11 months.
- No work history required: unlike CPP, OAS depends on residence, not contributions.
The OAS Recovery Tax (Clawback)
Once your net world income passes the threshold, you repay 15 cents of OAS for every dollar above it, and the repayment is collected through smaller monthly OAS payments. Income that counts includes RRIF and RRSP withdrawals, CPP, employer pensions, rental income, interest and capital gains. Eligible Canadian dividends are grossed up by 38% for this calculation, which surprises many retirees. TFSA withdrawals and TFSA growth generally do not count. Typical planning moves include splitting eligible pension income with a spouse, spreading large withdrawals across years, and using the TFSA for extra spending.
Working Past 65
Since forced retirement is gone, you can keep working while collecting CPP and OAS. Your wages are taxable and count toward the clawback calculation. If you are collecting CPP and working before 65, contributions are mandatory. Between 65 and 70 contributions are optional, and choosing to contribute earns you post-retirement benefits.
Your October Checklist
- Log in to My Service Canada Account and confirm your direct-deposit details before October 28.
- If you turn 65 soon, check whether you need to apply. OAS is sometimes automatic, but CPP always requires an application.
- Estimate your 2026 net income against the $95,323 threshold, especially if you plan RRSP, RRIF or investment-property withdrawals before year-end.
- Watch for the CRA’s 2027 pensionable earnings announcement in early November.
- Treat any post that promises a new bonus, extra payment or sudden age rule as unverified until you find it on Canada.ca.
Official Sources
| Purpose | Official link |
| CPP and OAS main portal | CLICK HERE |
| OAS payment amounts and latest adjustment | CLICK HERE |
| CPP and OAS maximum amounts (quarterly statistics) | CLICK HERE |
| OAS pension recovery tax thresholds | CLICK HERE |
| Government benefits payment calendar | CLICK HERE |
| CPP and OAS 2026 payment date calendar (PDF) | CLICK HERE |
| CRA announcement of 2025 pensionable earnings (shows usual timing) | CLICK HERE |
| Canadian Human Rights Act (full text) | CLICK HERE |
| My Service Canada Account | CLICK HERE |
| Service Canada phone line | 1-800-277-9914 |
Disclaimer
This article is general information, not financial, tax or legal advice. Benefit amounts change quarterly and thresholds change yearly, so confirm figures on Canada.ca or with Service Canada before making decisions.
Frequently Asked Questions (JSON-LD)
Did Canada end mandatory retirement at 65 in November 2025?
No. There was no such reform in November 2025. Mandatory retirement based on age alone was phased out earlier, with provinces acting first and the federal repeal receiving Royal Assent on December 15, 2011 and taking effect on December 15, 2012.
Is there a mandatory retirement age in Canada today?
No. An employer cannot force you to retire because of age alone. A narrow exception exists only where the employer can prove an age limit is a genuine occupational requirement.
How much is the maximum OAS pension from October 2026?
After the 1.4% increase, the maximum OAS pension is $762.50 per month for ages 65 to 74 and $838.75 per month for ages 75 and over. Your actual amount depends on your years of residence in Canada after age 18.
When are the next CPP and OAS payments?
The remaining 2026 deposit dates are Wednesday, October 28, Thursday, November 26 and Tuesday, December 22. Always confirm on the official Canada.ca benefits calendar.
What is the maximum CPP retirement pension in 2026?
The maximum for a new pension starting at age 65 is $1,507.65 per month. Most people receive less because the amount depends on contributions and the age you start
Is the $1,508 CPP payment a new bonus?
No. It is simply a rounded version of the 2026 maximum CPP retirement pension at 65. It is not an extra payment and it is not what the average retiree receives.
What is the earliest age to start CPP and OAS?
CPP can start as early as age 60, with a permanent reduction of 0.6% per month before 65. OAS cannot start before 65, but both can be deferred to age 70 for a higher monthly amount.
What is the OAS clawback threshold?
For July 2026 to June 2027 the threshold is $93,454, based on 2025 net world income. For July 2027 to June 2028 it is $95,323, based on 2026 income. You repay 15 cents of OAS for every dollar above the threshold.
When will the 2027 CPP maximum pensionable earnings be announced?
The Canada Revenue Agency usually publishes the next year’s figures around the start of November. The 2026 ceiling is $74,600, and any 2027 number seen before the official release is only a projection.
Can I keep working after 65 while collecting CPP and OAS?
Yes. Your employment income is taxable and counts toward the OAS recovery tax calculation, but there is no rule requiring you to stop working at 65.