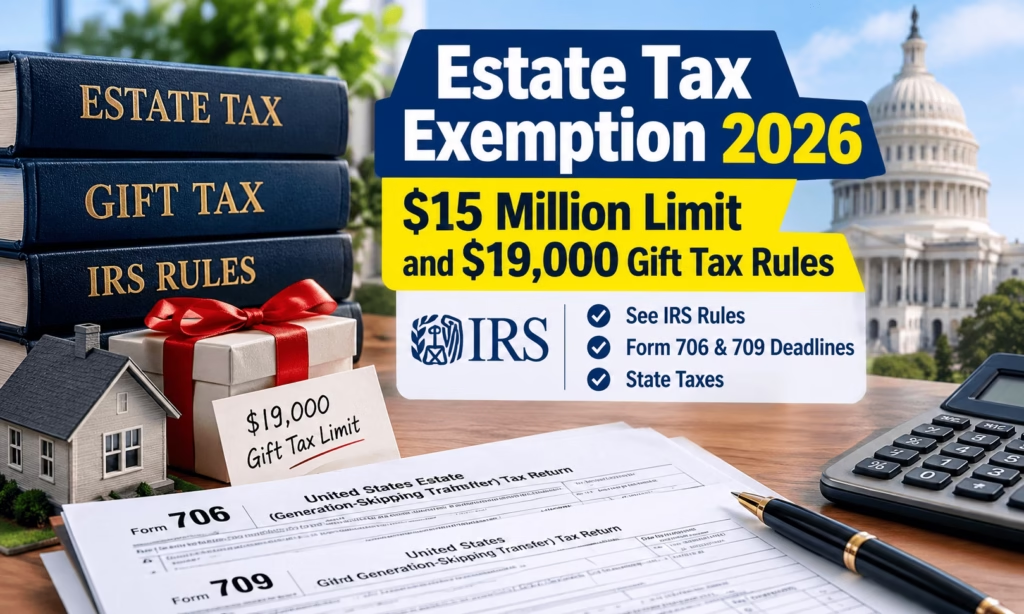
Estate Tax Exemption 2026: Most American families will never owe a dollar of federal estate tax this year. That is the headline behind the estate tax exemption 2026, which now sits at $15 million per person after the One Big Beautiful Bill Act locked it in and the IRS confirmed it in Revenue Procedure 2025-32. A married couple can shield up to $30 million, and anything above that is taxed at a flat 40 percent. Alongside it, the annual gift tax exclusion holds steady at $19,000 per recipient, which means a parent, grandparent or friend can hand over that much to as many people as they like without filing a gift tax return or touching the lifetime exemption. The two numbers work together, and misreading either one can be costly. We will be updating this article monthly.
The timing matters for a simple reason. For years, families and advisers planned around a scheduled drop in the exemption to roughly half its size at the end of 2025. That cliff is gone. The $15 million figure is now permanent, and it will be adjusted for inflation beginning in 2027, so the old rush to give assets away before a deadline has mostly faded. What has not faded is the paperwork, the state-level taxes, and the planning mistakes that catch heirs off guard. This guide walks through the federal estate tax exemption, the gift tax limit, the filing rules, and the practical steps families are taking right now, with the official sources listed so you can check every figure yourself.
Estate Tax Exemption 2026 Key Highlights
| Item | 2026 Figure | What It Means |
|---|---|---|
| Federal estate tax exemption (per person) | $15,000,000 | Amount a person can leave at death before federal estate tax applies |
| Married couple combined exemption | $30,000,000 | Possible when the surviving spouse uses portability correctly |
| 2025 exemption for comparison | $13,990,000 | Increase of $1,010,000 in one year |
| Annual gift tax exclusion | $19,000 per recipient | Same as 2025, no gift tax return needed below this level |
| Annual exclusion with gift splitting | $38,000 per recipient | Married couples who elect to split gifts |
| Gift to a non-citizen spouse | $194,000 | Annual limit for 2026 under the marital deduction rules |
| Estate and gift tax rate | 40% | Applies only to the amount above the exemption |
| Generation-skipping transfer exemption | $15,000,000 | Matches the estate tax exemption |
| Gift tax return (Form 709) due date | April 15 of the following year | Required if gifts exceed the annual exclusion |
| Estate tax return (Form 706) due date | 9 months after date of death | A 6-month extension is available |
| Next official update | Late October or November 2026 | IRS publishes 2027 inflation-adjusted amounts |
What Changed in 2026 and Why the $15 Million Limit Is Permanent
Before July 2025, the law was set to cut the basic exclusion amount sharply once the 2017 tax cuts expired. Planners had been warning clients for years that the exemption could fall to somewhere around $7 million per person. Congress removed that threat when it passed the One Big Beautiful Bill Act, which set the basic exclusion amount at $15 million for 2026 and made it permanent, with annual inflation indexing starting in 2027.
The jump from $13.99 million in 2025 to $15 million in 2026 is the largest single step many estate lawyers have seen outside of a major tax act. It means an additional $1.01 million per person, or $2.02 million per couple, can pass free of federal transfer tax. For families who had already used their full exemption through earlier gifts, that extra room is new capacity to give more.
The exemption is also unified. The same $15 million covers lifetime taxable gifts and assets left at death. Every dollar of taxable gifts made during life reduces what remains for the estate. That linkage is the single most misunderstood part of the system, and it is why the gift tax limit 2026 and the estate tax exemption have to be read together rather than as two separate allowances.
Gift Tax Limit 2026: How the $19,000 Annual Exclusion Works
The annual gift tax exclusion is the quietest tool in estate planning and one of the most effective. In 2026 you can give up to $19,000 to any one person, in any form, without the gift counting against your lifetime exemption and without filing a return. The limit applies per recipient, not per year in total. A grandmother with four grandchildren and two adult children can give $19,000 to each of the six, which is $114,000 in a single year, with no tax paperwork.
Married couples can combine their exclusions. If both spouses agree to split gifts, each recipient can receive $38,000. Gift splitting does require filing Form 709 even when no tax is owed, which surprises many couples who assumed that staying under the limit meant skipping the form altogether.
A few rules shape how the exclusion works in practice:
- The gift must be a present interest. Money placed in certain trusts may not qualify unless the beneficiary has a right to withdraw it.
- Tuition paid directly to a school and medical bills paid directly to a provider do not count as gifts at all, no matter how large they are.
- Gifts to a spouse who is a U.S. citizen are unlimited. Gifts to a spouse who is not a U.S. citizen are capped at $194,000 for 2026 before they begin using the lifetime exemption.
- Gifts above the annual exclusion are not automatically taxed. They simply reduce the $15 million lifetime amount, and a return is filed to track it.
NY POWER Rebate Check: Who Gets $100 to $200 and When?
Social Security Changes October 2026: 4 Updates That Could Affect Your Benefits
Estate Tax Calculator 2026: Estimate Your Federal Bill in Seconds
Rules are easier to grasp with numbers in front of you. The free estate tax calculator that accompanies this article lets you enter the value of an estate, add taxable gifts already reported on past Form 709 filings, include any unused exclusion inherited from a late spouse, and see the estimated federal tax at the 40 percent rate. A second panel shows how many people you can give to each year using the $19,000 limit and what that totals in tax-free transfers.
Estate Tax Calculator 2026
Federal estimate using the $15 million exemption per person and the 40% rate. Planning aid only.
| Taxable estate after deductions | – |
| Add: prior taxable gifts | – |
| Total transfers subject to tax | – |
| Exemption available | – |
| Amount above exemption | – |
Annual Gift Tax Exclusion Planner 2026
Annual exclusion is $19,000 per recipient, or $38,000 when spouses split gifts.
| Annual exclusion per recipient | – |
| Tax-free total this year | – |
| Amount counting against lifetime exemption | – |
The calculator is a planning aid, not a filing tool. It does not account for deductions such as debts, administration costs, charitable gifts or state taxes, which can lower a taxable estate in real life. Treat the result as a first estimate and bring it to a tax professional before acting on it.
How Much Federal Estate Tax Will an Estate Owe?
The math is simpler than the paperwork. Federal estate tax applies only to the taxable estate above the available exemption, and the rate is a flat 40 percent. These examples assume no prior taxable gifts and no deductions.
| Scenario | Taxable Estate | Exemption Available | Federal Estate Tax |
|---|---|---|---|
| Single person, $12 million estate | $12,000,000 | $15,000,000 | $0 |
| Single person, $15 million estate | $15,000,000 | $15,000,000 | $0 |
| Single person, $20 million estate | $20,000,000 | $15,000,000 | $2,000,000 |
| Single person, $30 million estate | $30,000,000 | $15,000,000 | $6,000,000 |
| Married couple, $28 million combined, portability used | $28,000,000 | $30,000,000 | $0 |
| Married couple, $28 million combined, portability missed | $28,000,000 | $15,000,000 | Possible tax on the second death |
The last two rows show why portability, covered next, deserves attention even for families who do not feel wealthy. Rising home values, retirement accounts, life insurance and business interests can push a combined estate higher than people expect.
Portability and the $30 Million Married Couple Exemption
The headline of $30 million for a couple is real, but it is not automatic. When the first spouse dies, any exemption they did not use can be transferred to the surviving spouse. That transferred amount is called the deceased spousal unused exclusion, or DSUE. To claim it, the executor must file a timely Form 706 and make the portability election, even if no estate tax is due and the estate is well below the filing threshold.
Skipping this step is one of the costliest oversights in estate planning. A surviving spouse who inherits a modest estate today can end up well above the exemption decades later after investments grow. Without a portability election, the late spouse’s unused amount is simply lost.
How to File: Form 706 and Form 709 Explained
There is no application to submit to claim the exemption itself. The exemption applies automatically. What families must do is file the correct return at the right time, depending on whether the event is a gift or a death.
Form 709, the United States Gift and Generation-Skipping Transfer Tax Return, is filed by the donor. It is required when a person gives more than the annual exclusion to one recipient, when spouses split gifts, or when a gift of a future interest is made. It is due on April 15 of the year after the gift, the same day as the income tax return, and an extension of the income tax return also extends Form 709.
Form 706, the United States Estate and Generation-Skipping Transfer Tax Return, is filed by the executor. It is required when the gross estate plus adjusted taxable gifts exceeds the exemption for the year of death. For anyone who dies in 2026, that threshold is $15 million.
The usual steps for an estate are:
- Gather the date-of-death values of every asset, including real estate, brokerage accounts, retirement plans, life insurance, business interests and personal property.
- Obtain appraisals for property that does not have an obvious market price, such as a closely held business, farmland or art.
- List debts, funeral expenses, administration costs and charitable bequests that qualify as deductions.
- Total prior taxable gifts from earlier Form 709 filings.
- Complete Form 706, elect portability if a spouse survives, and attach the supporting schedules.
- File with the IRS and pay any tax due by the deadline.
Executors who need more time can file Form 4768 for an automatic six-month extension to file. That extension does not extend the time to pay, which is a point of frequent confusion.
SNAP Benefits Changes: Who Is Losing Food Aid Now
Medicare Open Enrollment 2026: What to Check Before December 7
Trump $5000 Dividend Check: Is It Real, Who Would Qualify and When Could Payments Start?
Processing Time: How Long Does the IRS Take After You File?
The IRS does not publish a fixed processing deadline for estate tax returns, and timing varies with complexity and the return’s accuracy. A well-prepared return with clean valuations usually moves faster than one that triggers questions about appraisals.
After a Form 706 is filed, the IRS may issue an estate tax closing letter, which confirms the return was accepted as filed or after examination. Executors can request this letter through the IRS online payment system after the return has been processed, and practitioners commonly report waiting several months, often around six, before it is available. Many executors wait for the closing letter before distributing all of the estate’s assets, because it gives comfort that no further tax is likely to be asked for.
Payment Schedule: When Estate and Gift Tax Is Due
| Return | Who Files | Filing Deadline | Payment Deadline |
|---|---|---|---|
| Form 706 estate tax return | Executor | 9 months after date of death | 9 months after date of death |
| Form 706 with extension (Form 4768) | Executor | Up to 15 months after date of death | Still 9 months after date of death unless a separate payment extension is granted |
| Form 706 for portability only | Executor | Timely filing preferred, late relief may be available up to 5 years | No tax due if below the threshold |
| Form 709 gift tax return | Donor | April 15 of the following year | April 15 of the following year |
State Estate Tax and Inheritance Tax
A federal exemption of $15 million does not protect an estate from state taxes. A group of states and the District of Columbia run their own estate taxes with much lower thresholds, and several others charge an inheritance tax on the people who receive the assets.
States with an estate tax include Connecticut, Hawaii, Illinois, Maine, Maryland, Massachusetts, Minnesota, New York, Oregon, Rhode Island, Vermont and Washington, along with the District of Columbia. Some of these thresholds are only a few million dollars. Oregon and Massachusetts, for example, begin taxing at levels far below the federal limit, and Washington revised its rates and exemption in 2025. Thresholds and rates change often, so check the state revenue department before relying on any figure.
Inheritance taxes work differently. They fall on the beneficiary rather than the estate, and the rate depends on the relationship to the person who died. Kentucky, Maryland, Nebraska, New Jersey and Pennsylvania are among the states that have them. Spouses are usually exempt, and children often pay little or nothing, while more distant relatives and friends can face higher rates.
A person who dies owning a home in a state with an estate tax can owe state tax even when the federal bill is zero. Families with property in more than one state should look at where each asset is located, because real estate is generally taxed by the state where it sits.
Smart Planning Moves Families Are Discussing Right Now
With the exemption settled, planning has moved from deadline-driven gifting to steady, practical housekeeping. Common steps include:
- Using the annual exclusion every year. Unused annual exclusions do not carry forward, so a missed year cannot be recovered.
- Paying tuition and medical bills directly to the institution instead of reimbursing family members.
- Reviewing beneficiary designations on retirement accounts and life insurance so they match the estate plan.
- Making the portability election at the first death, even when the estate is small.
- Thinking about income tax basis. Assets held until death generally receive a step-up in basis, which can erase capital gains for heirs. Giving away highly appreciated assets during life can pass along the donor’s original basis and a larger future tax bill.
- Funding education through 529 plans, which allow a special election to treat up to five years of contributions as made at once. For 2026 that means up to $95,000 per beneficiary, or $190,000 for a married couple, subject to the usual rules.
What Comes Next: The 2027 Estate Tax Exemption Outlook
The IRS usually releases its inflation-adjusted figures for the next year in October or November, so official 2027 amounts are expected within weeks. Until then, any 2027 number is a projection, not a confirmed figure. Analysts building estimates from inflation data have pointed to a 2027 exemption somewhere in the range of roughly $15.3 million to $15.5 million per person, and an annual gift exclusion that either stays at $19,000 or rises to $20,000 depending on how the inflation formula rounds. These are estimates from private projections, not IRS numbers, and they may move when the Revenue Procedure is published.
We will update this article when the IRS releases the official 2027 figures. For planning purposes, the safe course is to rely on the confirmed 2026 numbers and revisit your plan once the new amounts are public.
Federal Pay Freeze 2027: Who Gets No Raise and Who Gets 3.8%
Social Security COLA by State: Which Retirees Get the Biggest 2027 Raise and Why?
Official Resources and Links for Estate and Gift Tax
| Resource | Best Used For | Official Link |
|---|---|---|
| IRS Estate Tax page | Rules, thresholds and filing overview | https://www.irs.gov/businesses/small-businesses-self-employed/estate-tax |
| IRS Gift Tax page | Annual exclusion and Form 709 guidance | https://www.irs.gov/businesses/small-businesses-self-employed/gift-tax |
| Form 706 | Estate tax return and portability election | https://www.irs.gov/forms-pubs/about-form-706 |
| Form 709 | Gift tax return | https://www.irs.gov/forms-pubs/about-form-709 |
| Form 4768 | Extension to file Form 706 and pay estate tax | https://www.irs.gov/forms-pubs/about-form-4768 |
| IRS Revenue Procedure 2025-32 | 2026 inflation adjustments | https://www.irs.gov/pub/irs-drop/rp-25-32.pdf |
| IRS Online Account | Check payments and balances | https://www.irs.gov/payments/your-online-account |
| IRS Pay Online (Direct Pay) | Pay estate or gift tax | https://www.irs.gov/payments/direct-pay |
| IRS Free File and tax help | Income tax filing support | https://www.irs.gov/filing |
| Pay.gov | Request an estate tax closing letter | https://www.pay.gov |
FAQs About the Estate Tax Exemption 2026
What is the estate tax exemption for 2026?
The federal estate tax exemption for 2026 is $15 million per person. A married couple can combine for up to $30 million if the surviving spouse benefits from portability.
What is the gift tax limit for 2026?
The annual gift tax exclusion for 2026 is $19,000 per recipient, unchanged from 2025. Married couples who split gifts can give $38,000 per recipient.
Do I have to pay tax if I give someone more than $19,000?
Not necessarily. Gifts above $19,000 require a Form 709, but they only reduce your $15 million lifetime exemption. Actual gift tax is due only after the lifetime amount is used up.
Is the $15 million exemption permanent?
Yes, under the One Big Beautiful Bill Act it has no scheduled expiration and will be adjusted for inflation each year starting in 2027. Congress can still change the law in the future.
What is the federal estate tax rate in 2026?
The rate is a flat 40 percent on the portion of an estate above the available exemption.
Who pays the estate tax, the heirs or the estate?
The estate pays federal estate tax before assets are distributed. The executor is responsible for filing the return and paying the tax.
Does the exemption apply to life insurance and retirement accounts?
Yes. These assets count toward the gross estate when the deceased owned them or had control over them, so they can push an estate above the threshold.
When is the estate tax return due?
Form 706 is generally due nine months after the date of death, and an automatic six-month extension to file is available with Form 4768.
How much can you inherit without paying federal tax?
Beneficiaries do not owe federal tax on an inheritance. The estate pays any federal estate tax, and only estates above $15 million per person are affected. A few states charge inheritance tax to recipients.
Do I need to report gifts to the IRS?
You need to file Form 709 only if gifts to one person exceed $19,000, if you split gifts with a spouse, or if you give a future interest. Smaller gifts do not have to be reported.
What happens if the estate is larger than $15 million?
The amount above the exemption is taxed at 40 percent. Planning, deductions such as the marital and charitable deductions, and the use of trusts can reduce the taxable amount.
Do states have their own estate tax?
Yes. A group of states and the District of Columbia charge estate tax at much lower thresholds, and some states also have an inheritance tax. Check your state’s rules.
Can I give away money to avoid estate tax?
Gifting can reduce an estate, but gifts above the annual exclusion reduce your lifetime exemption and gifted assets lose the step-up in basis at death. Giving should be balanced against your own financial needs.
Conclusion: What Families Should Do Now
The estate tax exemption 2026 is higher than ever at $15 million per person, it is now permanent, and the $19,000 annual gift tax exclusion gives every family a steady way to move wealth with no tax and no return. For most households the practical lesson is not about paying tax. It is about getting the paperwork, beneficiary designations and spousal elections right so that nothing is lost.
If your estate or your spouse’s estate could approach the exemption, or if you live in a state with its own estate tax, a short meeting with an estate attorney or tax professional now is worth far more than a rushed fix later. Check the IRS links above for the latest forms, watch for the official 2027 numbers due this autumn, and treat every projected figure as provisional until the IRS publishes it.
Medicare Part D Changes 2027: $2,400 Cap, $700 Deductible
FEHB Open Season 2027 Dates: November 9 to December 14, Premiums Up 10.9% and What to Do Now