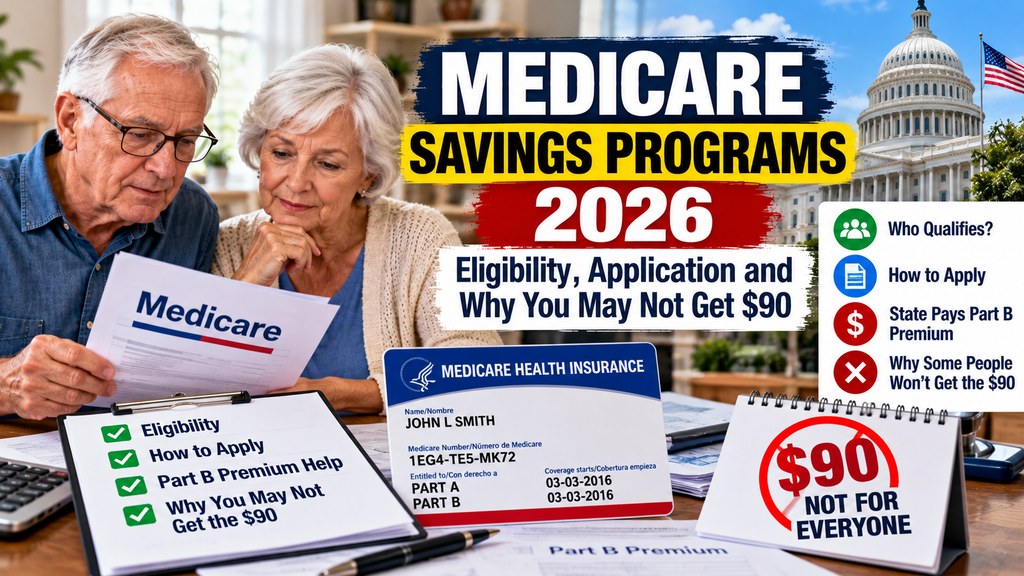
Medicare Savings Programs 2026: Millions of Americans enrolled in Medicare must manage monthly premiums, medical deductibles, prescription expenses, and other out-of-pocket costs. For people living on Social Security, a pension, or a limited income, even a relatively small monthly premium can put pressure on a household budget. The Medicare Savings Programs (MSPs) may help eligible beneficiaries by having their state Medicaid agency pay some or all of their Medicare premiums and, under certain programs, additional Medicare cost-sharing.
In 2026, the standard Medicare Part B premium is $202.90 per month, according to the Centers for Medicare & Medicaid Services (CMS). That amounts to $2,434.80 over 12 months before considering any other eligible assistance. There is also a separate issue attracting attention this October: a one-time $90 Medicare Part B premium rebate announced by CMS for certain beneficiaries. Not everyone enrolled in Medicare will receive that payment.
People receiving Medicaid premium assistance, including many beneficiaries whose Part B premiums are paid through a Medicare Savings Program, are excluded under the published rebate criteria. People enrolled in Medicare Advantage are also ineligible. These are two different forms of assistance. Medicare Savings Programs provide ongoing help to eligible people through their state, while the $90 rebate is a one-time payment with separate eligibility rules. Here is how the programs work, who may qualify in 2026, how to apply, and why some beneficiaries should not expect the $90 payment.
What Are Medicare Savings Programs?
Medicare Savings Programs are state-administered Medicaid programs that help eligible people with limited income and resources pay certain Medicare costs.
Depending on the program, assistance may cover:
- Medicare Part B monthly premiums.
- Medicare Part A premiums for people who must pay them.
- Medicare deductibles, coinsurance, and copayments for Medicare-covered services under the applicable program.
The state Medicaid agency determines eligibility. The four main Medicare Savings Programs are Qualified Medicare Beneficiary (QMB), Specified Low-Income Medicare Beneficiary (SLMB), Qualifying Individual (QI), and Qualified Disabled and Working Individual (QDWI). Each has different rules and provides different types of assistance.
The key benefit for many older adults is the possibility of having their monthly Part B premium paid by the state. This can reduce the amount deducted from Social Security benefits or otherwise owed for Medicare coverage.
However, qualifying for one program does not automatically mean that a person qualifies for all four. The state reviews the household’s income, resources, Medicare status, and other applicable requirements.
SSA COLA 2027 Update: SSA Will Announce the Raise on October 14, and Experts Expect 3.5%
SNAP Benefits November 2026: Payment Dates, New Rules, Eligibility and Maximum Benefits
Trump Accounts Dell $250 Grant: Did Deposits Actually Start Monday? Here’s Who’s Actually Been Paid
2026 Medicare Savings Program Income and Resource Limits
The federal limits below apply to most states and the District of Columbia. Alaska and Hawaii have higher income limits. Some states also use more generous eligibility rules, so a person whose income or resources exceed the federal figures may still qualify.
| Program | Individual monthly income limit | Married couple monthly income limit | Individual resource limit | Couple resource limit |
|---|---|---|---|---|
| QMB | $1,350 | $1,824 | $9,950 | $14,910 |
| SLMB | $1,616 | $2,184 | $9,950 | $14,910 |
| QI | $1,816 | $2,455 | $9,950 | $14,910 |
| QDWI | $5,405 | $7,299 | $4,000 | $6,000 |
Important: These are federal screening figures, not a guarantee of approval. State rules may disregard certain income or resources, and the QDWI program has different eligibility conditions from the other three programs. Ask your state agency to assess your situation before deciding that you earn too much or have too many resources.
What Counts as Income?
Depending on the rules used by your state, income may include Social Security payments, pensions, wages, and other income sources. The state determines how the applicable exclusions and deductions affect the income used for eligibility. Do not simply compare your Social Security deposit with the income limit and assume you cannot qualify.
What Counts as Resources?
Resources generally refer to certain assets, such as money in bank accounts and other countable financial holdings. The rules identify which resources count and which may be excluded. The exact treatment of assets depends on the applicable program rules and state policy. Check with the Medicaid agency before making decisions based on your savings or property.
The Four Medicare Savings Programs Explained
1. Qualified Medicare Beneficiary (QMB)
The QMB program provides the broadest Medicare cost-sharing protections among the main Medicare Savings Programs. Eligible beneficiaries can receive help with their Part B premiums and, when applicable, Part A premiums. QMB also protects beneficiaries from being billed by Medicare providers for Medicare-covered deductibles, coinsurance, and copayments, subject to the program’s rules.
For 2026, the federal monthly income limits in most states are $1,350 for an individual and $1,824 for a married couple. QMB is especially important for people who have difficulty paying both their premiums and the bills that can arise when they receive covered medical services. If you qualify, tell your healthcare providers that you have QMB and show your Medicare card along with your Medicaid or QMB documentation when requested.
2. Specified Low-Income Medicare Beneficiary (SLMB)
SLMB helps eligible people pay their Medicare Part B premiums. It does not provide the same broad Medicare cost-sharing protection as QMB. The 2026 federal monthly income limits in most states are:
- Individual: $1,616.
- Married couple: $2,184.
Applicants must have Medicare Part A and Part B. Eligible SLMB beneficiaries also receive Extra Help with Medicare prescription drug costs under the rules described by Medicare.gov. SLMB may be relevant to people whose income is too high for QMB but remains within the applicable SLMB limits.
3. Qualifying Individual (QI)
The QI program also helps eligible beneficiaries pay their Part B premiums. The 2026 federal monthly income limits in most states are $1,816 for an individual and $2,455 for a married couple. QI has an important difference: eligible people generally must apply every year, and states approve applications on a first-come, first-served basis. Priority is given to people who received QI assistance in the previous year. You cannot receive QI if you qualify for other Medicaid coverage or benefits that make you ineligible for the program.
If you qualify for QI, the state can pay your Part B premium. Because the program has its own eligibility and funding rules, submit your application promptly and ask your state whether you need to renew.
4. Qualified Disabled and Working Individual (QDWI)
QDWI is different from QMB, SLMB, and QI. It helps certain people with disabilities who returned to work, lost their premium-free Medicare Part A eligibility because of work, and meet the program’s requirements. QDWI pays the Part A premium, not the Part B premium. The federal 2026 monthly income limits in most states are $5,405 for an individual and $7,299 for a married couple, with resource limits of $4,000 and $6,000, respectively. Because the eligibility conditions are specific, contact your state Medicaid agency if you think you may qualify.
How to Apply for a Medicare Savings Program in 2026
Medicare Savings Programs are administered by state Medicaid agencies. You do not apply for them through a private Medicare Advantage plan, and you should not assume that enrolling in Medicare automatically enrolls you in an MSP. The official Medicare website directs applicants to their state agency for the application process.
Step 1: Start with the official federal directory of state Medicaid agencies: Medicaid.gov — State Medicaid Agencies Use the contact information for your state to locate its Medicare Savings Program application instructions.
Step 2: Tell the agency that you want to apply for a Medicare Savings Program. Ask it to screen you for QMB, SLMB, QI, and, if relevant, QDWI. This matters because the program you qualify for depends on your circumstances. An applicant who does not qualify for QMB may still qualify for another program.
Step 3: The state may ask for documents such as:
- Medicare card or proof of Medicare enrollment.
- Social Security benefit information.
- Pension or wage statements, if applicable.
- Bank or financial account information, when required.
- Identification and residency information.
- Marriage or household information, if relevant.
The exact documentation depends on the state’s application process.
Step 4: Use the application method accepted by your state. Some states offer online applications, while others may allow applications by mail, telephone, or in person. Keep a copy of your application and any confirmation or case number.
Step 5: If the agency requests additional documents, send them by the deadline stated in the notice. If you are unsure what is required, contact the agency rather than ignoring the request.
Step 6: Ask when your coverage begins and how the state will handle your Part B premium. If you are approved, keep the approval notice for your records. Do not assume a payment has been applied simply because you submitted an application. Wait for confirmation from the agency.
2027 COLA Estimate Changed Again: What Moved and 3 Smart Moves to Make Before October 14
Social Security Changes October 2026: SSA Announces Major Update for Retirees and Beneficiaries
SSI Payment Dates October 2026 to January 2027: Every Early Deposit Explained
Why Some Medicare Beneficiaries Will Not Get the $90 Rebate
The $90 rebate is separate from the Medicare Savings Programs. CMS published information in October 2026 describing a one-time payment intended to offset the October Medicare Part B premium for certain beneficiaries. According to the official guidance, most eligible people were expected to receive a direct deposit around October 8, while some were expected to receive a Treasury check later in October. The rebate is not a monthly Medicare benefit, and it is not an additional payment available to everyone who has Medicare.
Reason 1: Your State Already Pays Your Part B Premium
This is a key reason some people receiving Medicare Savings Program assistance will not receive the $90 rebate. CMS says the rebate is for eligible people enrolled in Original Medicare Part B who are not receiving premium assistance from Medicaid. If your state pays your Part B premium through an MSP, you fall within the group excluded by that condition.
In other words, the state may already be covering the premium that the rebate is intended to offset. Being excluded from the one-time rebate does not mean your Medicare Savings Program has been canceled.
Reason 2: You Are Enrolled in Medicare Advantage
CMS explicitly states that people enrolled in Medicare Advantage are not eligible for the one-time $90 rebate. This exclusion is tied to the published rules for the rebate. It does not, by itself, determine whether you qualify for a Medicare Savings Program. If you are enrolled in Medicare Advantage and need help with premiums or medical expenses, contact your state Medicaid agency to ask about MSP eligibility.
Reason 3: You Pay an Income-Related Monthly Adjustment Amount (IRMAA)
The published rebate criteria exclude beneficiaries who pay an Income-Related Monthly Adjustment Amount, commonly called IRMAA. This is an income-related surcharge that can increase Medicare premiums for certain beneficiaries. A beneficiary who pays IRMAA should not assume that the $90 payment will arrive simply because they are enrolled in Part B.
Reason 4: You Do Not Meet the Other Rebate Conditions
The official Medicare notice describes the rebate as applying to qualifying people enrolled in Original Medicare Part B who live in the United States and meet the published premium-assistance and IRMAA conditions. If you are unsure whether your situation meets the requirements, contact Medicare directly instead of relying on a general online article.
How to Check Whether Your $90 Rebate Is Coming
CMS provides separate contacts for checking rebate eligibility and payment status.
- To check eligibility: Call Medicare at 1-800-MEDICARE (1-800-633-4227).
- To check payment status: CMS says beneficiaries can contact the Social Security Administration at 1-800-772-1213 beginning October 15, 2026.
- If you are receiving MSP assistance: Ask your state Medicaid agency to confirm whether it pays your Part B premium and which program you are enrolled in.
Keep in mind that the rebate was described as a one-time October payment. It should not be confused with a recurring $90 monthly benefit or a new Medicare Savings Program.
Key Features between Medicare Savings Programs and the $90 Medicare Part B rebate
| Feature | Medicare Savings Program | $90 Medicare Part B rebate |
|---|---|---|
| Purpose | Helps eligible people pay Medicare premiums and, for certain programs, other covered costs | One-time payment to offset the October 2026 Part B premium |
| Who administers it? | State Medicaid agency | Federal Medicare/CMS process |
| Payment frequency | Ongoing assistance while eligible, subject to program rules | One-time payment |
| Part B premium help | QMB, SLMB, and QI may pay the Part B premium | Does not replace ongoing MSP assistance |
| People receiving Medicaid premium assistance | May qualify for the MSP itself | Excluded under the published rebate criteria |
| Medicare Advantage enrollees | MSP eligibility depends on state program rules and individual circumstances | Not eligible for this rebate |
| How to apply or check | Contact the state Medicaid agency | Contact Medicare or SSA as directed by CMS |
What If Your Income Is Slightly Above the Federal Limit?
Do not automatically rule yourself out. Medicare.gov and the Social Security Administration explain that states may use rules that disregard certain income or resources, allowing some people to qualify even when their finances exceed the federal figures shown in the standard table. The treatment of income and resources can vary by state. Your state agency is the right place to determine whether you qualify. If you have limited income but have not applied because you believe your Social Security payment is too high, ask for an eligibility screening. You may qualify for a program other than the one you initially considered.
FAQ’s
Can the state pay my Medicare Part B premium in 2026?
Yes. Eligible people may receive Part B premium assistance through QMB, SLMB, or QI. The state Medicaid agency decides eligibility under the applicable rules.
What is the income limit for Medicare Savings Programs in 2026?
For most states, the federal monthly limits are $1,350 for an individual under QMB, $1,616 under SLMB, and $1,816 under QI. Married-couple limits are $1,824, $2,184, and $2,455, respectively. State rules may be more generous.
Possible reasons include receiving Part B premium assistance through Medicaid, paying IRMAA, or being enrolled in Medicare Advantage. The published rebate criteria also require qualifying Original Medicare Part B enrollment and U.S. residence. Contact Medicare to verify your individual status.
Does not receiving the $90 rebate mean I am not eligible for Medicare Savings Programs?
No. The rebate and MSPs are separate. A person may be excluded from the rebate because the state already pays their Part B premium while still receiving valid MSP assistance.
Is the $90 rebate paid every month?
No. CMS describes it as a one-time $90 payment in October 2026, not a recurring monthly benefit.
Can I apply for an MSP if I already have Medicare Advantage?
Ask your state Medicaid agency. Medicare Advantage enrollment excludes you from the specific $90 rebate, but it does not automatically answer whether you qualify for a Medicare Savings Program.
Where do I apply for a Medicare Savings Program?
Apply through your state Medicaid agency. Use the official Medicaid.gov state agency directory to find the correct office.
Does QMB pay more than the Part B premium?
QMB can help with Part B premiums and certain Medicare-covered deductibles, coinsurance, and copayments. It also provides protections against provider billing for Medicare-covered services under the program’s rules.
Medicare Savings Programs can provide meaningful financial relief to eligible people who struggle with Medicare premiums and other medical expenses. In 2026, QMB, SLMB, and QI can help eligible beneficiaries pay their Part B premiums, while QMB offers additional cost-sharing protections.
The $90 rebate is a separate, one-time October 2026 payment with narrower eligibility conditions. People whose Part B premiums are already paid through Medicaid, people paying IRMAA, and people enrolled in Medicare Advantage are among those who should not expect the rebate under the published criteria.
If you need help paying Medicare costs, do not let the rebate rules stop you from applying for an MSP. Contact your state Medicaid agency, ask which program fits your circumstances, and request an official eligibility determination.
Also Read:
$200 Extra Social Security Payment: When Is It Being Approved, and Who Can Get It?
Trump $5000 Dividend Check: Latest Update on Cost, Eligibility and Payment Date
New York POWER Rebate Checks: $100 to $200 Payments Begin Landing in Mailboxes This Fall
SSA COLA 2027 Update: SSA Will Announce the Raise on October 14, and Experts Expect 3.5%