On October 14, the Social Security Administration confirmed what forecasters had been signaling for weeks: benefits for 76 million Americans will rise 3.6 percent in 2027. It is the biggest cost-of-living adjustment (COLA) since the 2023 increase and a clear step up from the 2.8 percent raise that took effect this January. The announcement arrived within hours of the September inflation report, which showed prices accelerating on the back of a sharp energy shock.
But a percentage is not a paycheck. Because the COLA is applied uniformly, the retiree collecting about $2,100 a month and the retiree collecting the maximum benefit of more than $4,100 get the same percentage and very different dollar raises. Then Medicare premiums, taxes, and the way benefits are structured reshape who actually feels ahead. This article breaks down the official numbers, compares the average retiree with those at the top of the benefit scale, and lays out the October and November dates and data points that matter between now and the first higher check.
Important news straight from SSA
Here is what the agency has made official:
- COLA: 3.6 percent for 2027, up from 2.8 percent for 2026.
- Who is covered: About 76 million Americans across Social Security and Supplemental Security Income (SSI). Nearly 72 million Social Security beneficiaries will see the increase beginning with January 2027 benefits, and about 7.3 million SSI recipients will see higher payments starting December 31, 2026. Some people receive both.
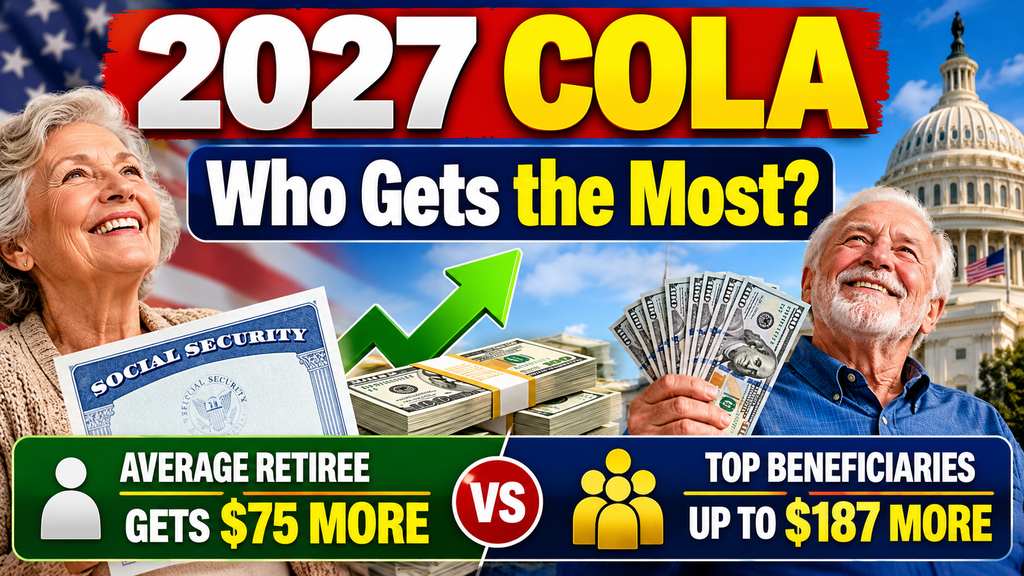
- Average retired worker: The monthly benefit rises from an estimated $2,095 to $2,170, an increase of about $75.
- Taxable maximum: The cap on earnings subject to the 6.2 percent Social Security payroll tax rises to $192,300 from $184,500.
- Earnings test: The limit for people under full retirement age rises to $25,560 a year, and to $67,920 for those who reach full retirement age during 2027.
The first higher payments will land in January for most people, though the timing depends on your payment group, which we cover below.
Where 3.6 percent comes from
By law, the COLA is tied to the Consumer Price Index for Urban Wage Earners and Clerical Workers, known as CPI-W. SSA compares the average CPI-W for July, August, and September of the current year with the same three-month average from the prior year. If the average rose, benefits rise by that percentage, rounded to the nearest tenth.
The September data made the final number possible. According to BLS, CPI-W reached an index level of 330.654 in September, up 3.9 percent over the previous 12 months. The broader CPI-U, the figure most headlines use, rose 3.7 percent over the same period, up from 3.4 percent in August. On a monthly basis, consumer prices climbed 0.6 percent in September after a 0.4 percent gain in August.
Energy did most of the damage. BLS reported that the energy index jumped 5.2 percent in September alone and is up 20.4 percent from a year earlier, with gasoline rising 9.1 percent in the month and roughly 34 percent over the year. Gasoline accounted for more than half of September’s overall increase. Core inflation, which strips out food and energy, was 2.6 percent, so the underlying trend is far milder than the headline suggests.
That gap explains why the COLA (3.6 percent) is lower than September’s CPI-W reading (3.9 percent). The COLA averages three months, and inflation was lower in July and August than in September. Beneficiaries effectively receive a raise based on the quarter, not on the most recent month, which matters because the fastest price increases came at the end of the window. It also means that if energy prices stay elevated, the cost-of-living pressure retirees feel in the fall may exceed what the 3.6 percent adjusts for.
There is also a point on composition. The CPI-W basket weights gasoline and transportation more heavily than the CPI-U does, which is why the wage-earner index ran hotter than the headline figure this quarter. Retirees tend to spend more on health care and housing than wage earners do, categories where this quarter’s increases were smaller. Medical care commodities, for example, were down 3.3 percent over the year in the September data. Whether a given retiree experiences the COLA as generous or stingy depends heavily on what they buy.
The average retiree: $75 a month
The SSA fact sheet estimates the average retired worker will see benefits move from $2,095 to $2,170 per month in January 2027. That is a gain of roughly $900 over a full year.
To put that in context, SSA’s monthly snapshot put the average retired-worker benefit at $2,084.40 in June 2026, and the fact sheet’s $2,095 starting point reflects the benefit level expected going into January. The 2026 COLA of 2.8 percent added an average of about $56 a month. The 2027 adjustment is therefore roughly a third larger in dollar terms.
For the typical retiree, that $75 does real work, but it has competition. A Medicare Part B premium increase, if it is deducted from the check, takes a bite right away (more on that below). And because average-benefit households spend a larger share of income on essentials such as food, utilities, and fuel, they feel energy-driven inflation more acutely than higher-income households do.
Who Gets 3 Deposits in October 2026? SSI and Social Security Recipients Explained
Who Will Get the ACA Payments in 30 States? $500 Refund Eligibility and Payment Schedule
Military Retirement Pay Raise: How Much More Will Retirees Get in 2027
Top beneficiaries: $149 a month
At the other end of the scale are retirees receiving the maximum benefit. For a worker retiring at full retirement age in 2026, that maximum was $4,152 a month, according to SSA. Applying 3.6 percent to that amount gives a raise of about $149 a month, bringing the check to roughly $4,301. That is our own calculation, shown for illustration; someone’s exact amount depends on their personal benefit and when they claimed.
The comparison is stark:
| Average retiree | Maximum-benefit retiree (illustrative) | |
|---|---|---|
| Monthly benefit before COLA | $2,095 | $4,152 |
| 3.6% COLA | +$75 | +$149 |
| Benefit after COLA | $2,170 | ~$4,301 |
| Annual raise | ~$900 | ~$1,794 |
In other words, the person at the top collects about twice the dollar increase of the average retiree, even though both receive exactly 3.6 percent. This is not a quirk or a loophole. It is how a percentage adjustment works: the larger your starting benefit, the larger the dollar gain.
One clarification is worth making, because it frequently causes confusion. SSA’s published maximum for a worker retiring at full retirement age moves from $4,152 in 2026 to $4,188 in 2027. That figure describes the ceiling for new retirees and is driven by wage indexing and the benefit formula, not by the COLA. The COLA is what lifts the checks of people already receiving benefits. So someone who retired at the maximum last year receives the COLA on top of their existing benefit, while a worker who reaches full retirement age in 2027 and has a maximum earnings record would start near $4,188. Retirees who delayed claiming past full retirement age can receive more than either number, and their COLA dollars rise accordingly.
Top earners also face a change on the other side of the ledger. The taxable maximum is climbing by $7,800. At the 6.2 percent employee rate, a worker earning at or above the cap pays up to about $483.60 more in Social Security payroll tax in 2027 than in 2026, and a self-employed worker, who pays both halves at 12.4 percent, up to about $967. These are our calculations from SSA’s published figures. The 7.65 percent combined employee tax rate and the 15.30 percent self-employed rate are unchanged.
Other groups: where the dollars land
The fact sheet also shows how the COLA plays out for different types of households. All receive 3.6 percent, but the dollar amounts diverge sharply:
| Beneficiary group | Before COLA | After COLA | Monthly gain |
|---|---|---|---|
| All retired workers | $2,095 | $2,170 | $75 |
| Aged couple, both receiving benefits | $3,238 | $3,355 | $117 |
| Aged widow(er) alone | $1,936 | $2,005 | $69 |
| Widowed mother and two children | $3,932 | $4,074 | $142 |
| Disabled worker, spouse and one or more children | $2,970 | $3,077 | $107 |
| All disabled workers | $1,642 | $1,701 | $59 |
The gain column is our arithmetic from SSA’s published averages. Two takeaways stand out. First, households with multiple beneficiaries, such as couples or families with dependent children, gain the most in raw dollars because several checks are rising at once. Second, single-income beneficiaries such as widows and disabled workers gain the least: about $69 and $59 a month respectively. These groups also tend to have fewer financial cushions, which is part of why advocates argue that a flat percentage understates the pressure on lower-income beneficiaries. Nancy Altman, president of Social Security Works, said this week that the increase does not fully capture the costs beneficiaries face.
SSI recipients, who have the lowest incomes, see their federal payment standard rise from $994 to $1,029 a month for an individual (about $35) and from $1,491 to $1,544 for a couple (about $53). Those are the smallest dollar increases in the program, yet for SSI recipients they represent a meaningful share of a very limited budget.
For people who work while receiving benefits or disability, SSA also raised the thresholds: substantial gainful activity rises to $1,770 a month for non-blind individuals ($2,950 for blind individuals), and the trial work period amount rises to $1,270.
The Medicare Part B
For most retirees, the raise is not the whole story, because Medicare Part B premiums are typically deducted directly from Social Security payments. The official 2027 Part B premium had not been announced as of this writing. CMS normally publishes it in November. The best available estimate comes from the 2026 Medicare Trustees Report, which projects a standard premium of $209.50 a month, up $6.60 from $202.90 in 2026, along with an annual deductible of about $292, up from $283. Treat those as projections until CMS confirms them.
Using the projected premium, here is how the net raise compares:
| Average retiree | Maximum-benefit retiree (illustrative) | |
|---|---|---|
| Gross COLA | +$75 | +$149 |
| Projected Part B increase | −$6.60 | −$6.60 |
| Net monthly gain (approx.) | ~$68 | ~$143 |
| Share of COLA absorbed by Part B increase | ~8.8% | ~4.4% |
The higher-benefit retiree keeps a larger fraction of the raise because the premium is a flat dollar amount. In absolute terms, the entire Part B premium (about $203 a month this year) represents roughly 9.7 percent of the average retiree’s benefit but only around 4.9 percent of a maximum benefit.
Two caveats apply. First, a federal “hold-harmless” rule generally prevents the Part B premium increase from exceeding the dollar increase in a person’s Social Security benefit, so for most people deducted from their check the net payment cannot shrink. Second, higher-income beneficiaries may owe income-related monthly adjustment amounts (IRMAA), surcharges on Part B and Part D premiums. IRMAA applies once income passes thresholds that start at $109,000 for individuals and $218,000 for joint filers in 2026, and the 2027 brackets are expected alongside the CMS announcement. Many top beneficiaries with significant pension, investment, or retirement-account income will pay surcharges that erode their larger dollar raise and are not shared by the average retiree.
On the drug side, the Part D figures for 2027 are already set: a $700 maximum deductible and a $2,400 annual out-of-pocket cap, up from $2,100 in 2026.
Tax Benefit
The tax treatment of benefits is not indexed to inflation. The income thresholds above which Social Security benefits become taxable have been fixed for decades. As a result, every COLA nudges more beneficiaries over the line, and those with substantial other income, typically the top benefit recipients, may owe federal income tax on up to 85 percent of their benefits. A $149 monthly raise can therefore be worth materially less after tax than a $75 raise for someone whose income sits below the thresholds and who owes nothing on benefits. The average retiree is more likely to keep close to the full amount, while the high-benefit retiree is more likely to see part of the gain taxed.
$400 Inflation Refund Checks 2026: New York’s Real Program, Fact-Checked
New York POWER Rebate Checks: $100 to $200 Payments Begin Landing in Mailboxes This Fall
So who gets the most?
The answer depends on what “most” means:
- Most in dollars: Top beneficiaries and multi-beneficiary households. A maximum-benefit retiree gains roughly twice what the average retiree does, about $149 versus $75 a month before premiums.
- Most after Medicare: Still the top beneficiaries, because the flat Part B increase eats a smaller share of their raise, unless IRMAA and taxes narrow the difference.
- Most in percentage terms: Everyone, at least on paper, gets 3.6 percent. SSI’s effective rate may differ slightly from rounding, but the program-level adjustment is the same.
- Most in relative importance: Lower-benefit households. For a widow collecting about $1,936 or a disabled worker collecting about $1,642, an extra $59 to $69 a month is a larger share of the budget, but it buys less against higher grocery, fuel, and utility bills.
October and November: what is happening and when
The COLA is announced, but the process is not finished. Here is the data and calendar for the next several weeks.
October 2026
- October 14: BLS released the September CPI report, and SSA announced the 3.6 percent COLA the same day. The September CPI-W stood at 330.654, up 3.9 percent from a year earlier. Headline CPI-U rose 3.7 percent, and core CPI rose 2.6 percent.
- October 15: The producer price index showed wholesale prices up 6.3 percent over the past 12 months in September, the largest annual rise since late 2022 and driven largely by energy. That is a signal that cost pressures may continue to pass through to consumers.
- SSI payments: Because November 1 falls on a Sunday, SSI recipients receive their November payment early, at the end of October, which means two SSI payments in October and none in November. This is a calendar shift, not an extra payment, so budget accordingly.
- Medicare open enrollment: Open enrollment for 2027 plan choices runs from October 15 through December 7, so the new Part D cap and plan costs are worth reviewing now.
November 2026
- Social Security payment dates: Beneficiaries who started before May 1997, or who receive both Social Security and SSI, are paid on Tuesday, November 3. Those with birthdays on the 1st through 10th are paid on Tuesday, November 10, one day early because Veterans Day falls on Wednesday, November 11. Birthdays on the 11th through 20th are paid on Wednesday, November 18, and those on the 21st through 31st on Wednesday, November 25.
- November 3: Midterm elections, with inflation and cost of living a prominent theme in coverage.
- November 18: The deadline to create a my Social Security account and enroll in paperless notices if you want to see your COLA notice online first. SSA says account holders can see their personal COLA up to three weeks earlier than by mail.
- Mid-November (expected): CMS announces the official 2027 Medicare Part B premium, deductible, and IRMAA brackets. The Trustees’ projection is $209.50 and $292, but the confirmed numbers may differ.
- Late November: Online COLA notices appear in the my Social Security Message Center, showing the new benefit amount after Medicare deductions for enrolled beneficiaries.
Looking a bit further out, mailed COLA notices go out during December, SSI recipients get their higher payment on December 31, and Social Security recipients see the 3.6 percent in January. The next inflation figures from BLS, covering October and November, will not affect the 2027 COLA, which is now locked in, but they will shape the conversation about whether 3.6 percent is enough and what the 2028 adjustment might look like.
What beneficiaries can do now
- Create or check your my Social Security account before November 18 and enroll in paperless notices to see your amount first.
- Watch for the CMS Part B announcement in November. Your actual net raise depends on it.
- Review your Medicare plan during open enrollment, especially Part D, where the 2027 deductible and out-of-pocket cap are changing.
- Check your tax picture. If you have other income, ask a tax professional how the larger benefit might affect taxation of benefits or IRMAA.
- Reassess your budget for energy costs. With gasoline and heating fuel up sharply, the energy-driven part of your spending may be rising faster than 3.6 percent.
- Watch the earnings test if you are working before full retirement age: the new limit is $25,560, and $1 in benefits is withheld for every $2 above it.
The 2027 COLA is good news by recent standards: 3.6 percent is the largest adjustment in four years and the sixth straight year at 2.5 percent or higher. But “who gets the most” has two honest answers. In percentage terms, nobody does, since everyone receives the same 3.6 percent. In dollar terms, the answer is those at the top: a maximum-benefit retiree gains about twice what the average retiree does, and multi-beneficiary households do better than single-income widows and disabled workers.
Once Medicare, taxes, and a volatile energy market enter the picture, the gap shifts again. A $6.60 premium increase is a small dent for a high-benefit retiree but a larger one for the average retiree, while IRMAA and taxes may claw back part of the top beneficiary’s advantage. The most useful way to read the COLA, then, is not as a single number but as a starting point: what matters is your own benefit, your Medicare costs, and what you spend your money on. November will fill in the last missing piece when CMS announces the official Medicare figures.
Note: Dollar gains for specific groups, the maximum-benefit comparison, and net-of-Part-B figures are calculated from the SSA fact sheet and the Trustees Report’s projected Part B premium, and are illustrative rather than official SSA amounts. This article is for general information and is not financial or tax advice.
Official Sources
- SSA: Social Security Announces 3.6 Percent Benefit Increase for 2027
- SSA: 2027 Cost-of-Living Adjustment Fact Sheet
- SSA: Cost-of-Living Adjustment (COLA) Information
- BLS: Consumer Price Index, September 2026
- CNBC: Social Security announces 3.6% COLA for 2027
- CNBC: September PPI and retail sales data
- Forbes: What the 3.6% raise means for Medicare patients
- Yahoo Finance: Social Security’s 2027 COLA is the biggest since 2023
- Kiplinger: Social Security payment schedule for 2026
- AMAC: Medicare costs in 2027